Clarivate Lands Its Promised Recurring-Growth Inflection, But Trimmed Guidance And A Price-Led ACV Keep The Recovery Small
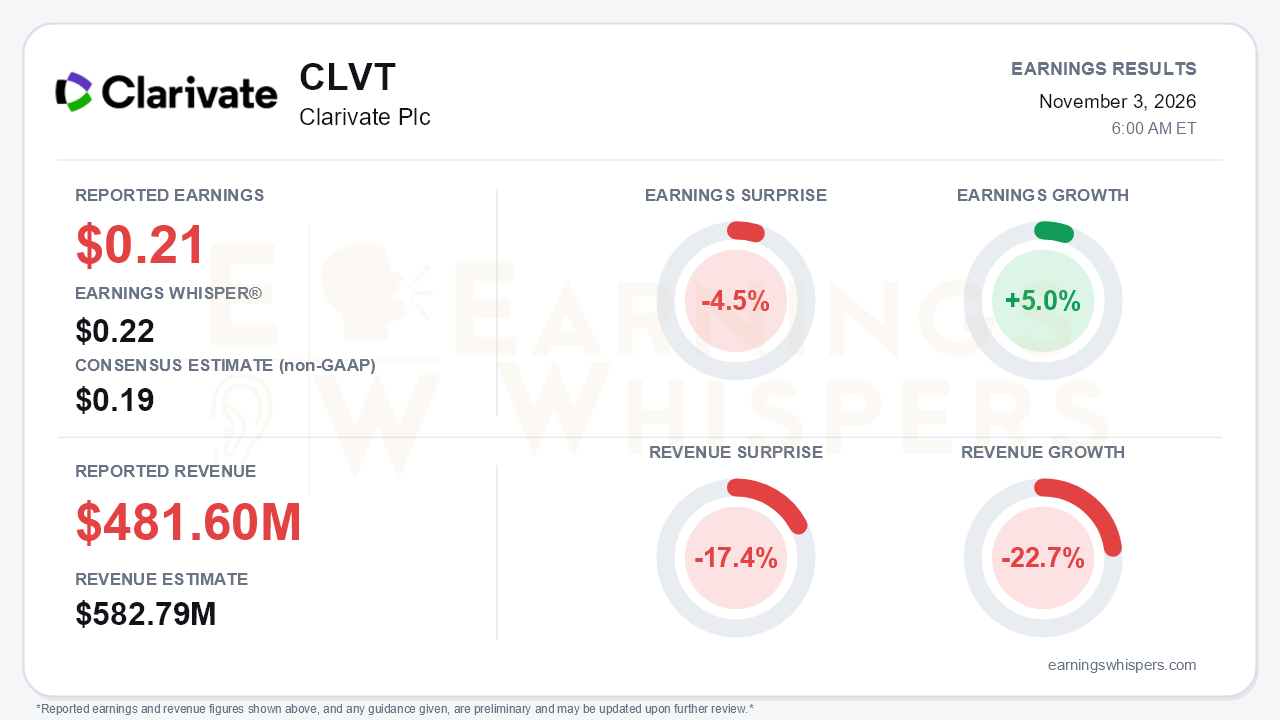
Clarivate's third quarter delivered the operating inflection management has been promising, but not the clean beat the market wanted. Adjusted EPS of $0.21 topped the $0.19 consensus and missed the $0.22 Earnings Whisper number by 4.5%. Revenue was $481.6 million, 17.4% below the $582.79 million consensus. That gap is largely presentational. The Life Sciences & Healthcare segment, sold on October 6, is now reported as discontinued operations. Including it, revenue was $567.9 million. The same issue clouds the growth comparisons. Earnings Whispers' normalized figures show earnings up 5.0% and revenue down 22.7%, while the company presents adjusted EPS rising from $0.18 and continuing-operations revenue falling 9.2%, mostly from disposals. The central tension is that the KPIs finally improved while the full-year organic and cash-flow targets moved lower.
The quality of the quarter is better on margins than on growth. Continuing-operations adjusted EBITDA slipped to $218.2 million from $222.2 million, but the margin widened to 45.3% from 41.9% as cost of revenues fell sharply. GAAP results look far worse. The net loss widened to $80.8 million, or $0.13 per share, from $28.3 million, driven by a $62.2 million non-cash LS&H goodwill impairment. Continuing-operations GAAP EPS was a flat $0.04 loss. Total organic growth was just 0.4%. Recurring revenue grew 1.3% organically, but a 12.4% organic decline in transactional revenue absorbed most of that gain. Free cash flow of $110.2 million edged down from $115.5 million. Net debt is falling but remains heavy at roughly $4.18 billion.
The call showed sequential progress that turnaround skeptics have been waiting for:
- Organic ACV growth reached 1.8%, up from 1.5% in Q2 and 1.6% in Q1.
- Recurring organic growth more than doubled from roughly 0.5% in Q2.
- Intellectual Property ACV turned positive for the first time in more than three years, and IP recurring revenue grew about 1% after being flat.
- Academia & Government held near 2% ACV and subscription growth.
Bears have legitimate ammunition on the composition, though. Management attributed the ACV gain mainly to roughly 3% pricing. That contrasts with the Q4 FY25 framing that volume was driving improvement. Clarivate also announced another wind-down of low-margin IP transactional products worth about 1% of revenue over one to two years. That will keep pressure on reported growth even as the mix improves.
Guidance cut both ways. On the positive side:
- Full-year adjusted EPS of $0.73 to $0.77 holds the $0.75 target.
- Margin expansion is now guided above 250 basis points, versus about 200 on every prior call.
- Organic cost savings rose to roughly $40 million from $25 million.
On the negative side:
- Organic ACV is now 1.75% to 2.25%, against the original 2% to 3%.
- Recurring organic growth narrowed to 1% to 1.5%.
- Total organic growth was lowered to about 0.5% from about 1%.
- Free cash flow is now $320 million to $340 million, down from a roughly $400 million midpoint earlier in the year.
Much of the cash-flow reduction is mechanical, reflecting the LS&H exclusion and about $30 million of deal costs. Higher taxes and working-capital use also contributed. The plan is now back-end loaded. Full-year EBITDA growth depends on Q4, which requires recurring growth above 2%, a level not seen in more than three years.
The catalyst list is real. LS&H closed early with $488.4 million of net proceeds earmarked for the 2028 and 2029 notes, and 2026 debt reduction totals about $875 million. Commercial wins include:
- a French national library modernization on Alma;
- USPTO adoption of Clarivate's trademark image search;
- more than 100 Web of Science Research Intelligence wins, up from 77 in Q2;
- an IP1 launch with 40-plus development partners and a 151-customer pipeline.
Management also offered early 2027 framing of higher ACV and recurring growth, free cash flow growth, lower leverage and easier second-half revenue comparisons.
Investor sentiment improved meaningfully heading into the report, rising from -0.52 to -0.21, though it remains negative. Price action has been far less forgiving. Shares stood at $1.66 before the release, down 6.7% from the $1.78 open after the July report. They were 25.3% below the 200-day moving average of $2.22. The stock has given back the entire post-July spike to $2.26 and set a 52-week low of $1.42 on October 7 before recovering about 17%. The AVWAP trend reading remains negative, consistent with a market that has not yet rewarded the operating progress.
The bottom line is that Clarivate delivered the KPI acceleration it promised, along with better margins and an early LS&H exit. However, organic growth is still barely positive, ACV gains lean on price, and full-year growth and cash-flow targets came down again. Q4 recurring growth above 2% is now the test of whether this inflection is durable or merely incremental.
Read our earnings preview for Clarivate Plc: https://www.earningswhispers.com/article/CLVT/21466
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| 8 hours | |
| Nov-02 | |
| Oct-26 | |
| Oct-22 | |
| Oct-15 | |
| Oct-06 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-17 | |
| Sep-17 | |
| Aug-06 | |
| Jul-29 |
