DuPont Tests Its Beat-And-Raise Streak As Water Softness And Cost Pressures Linger
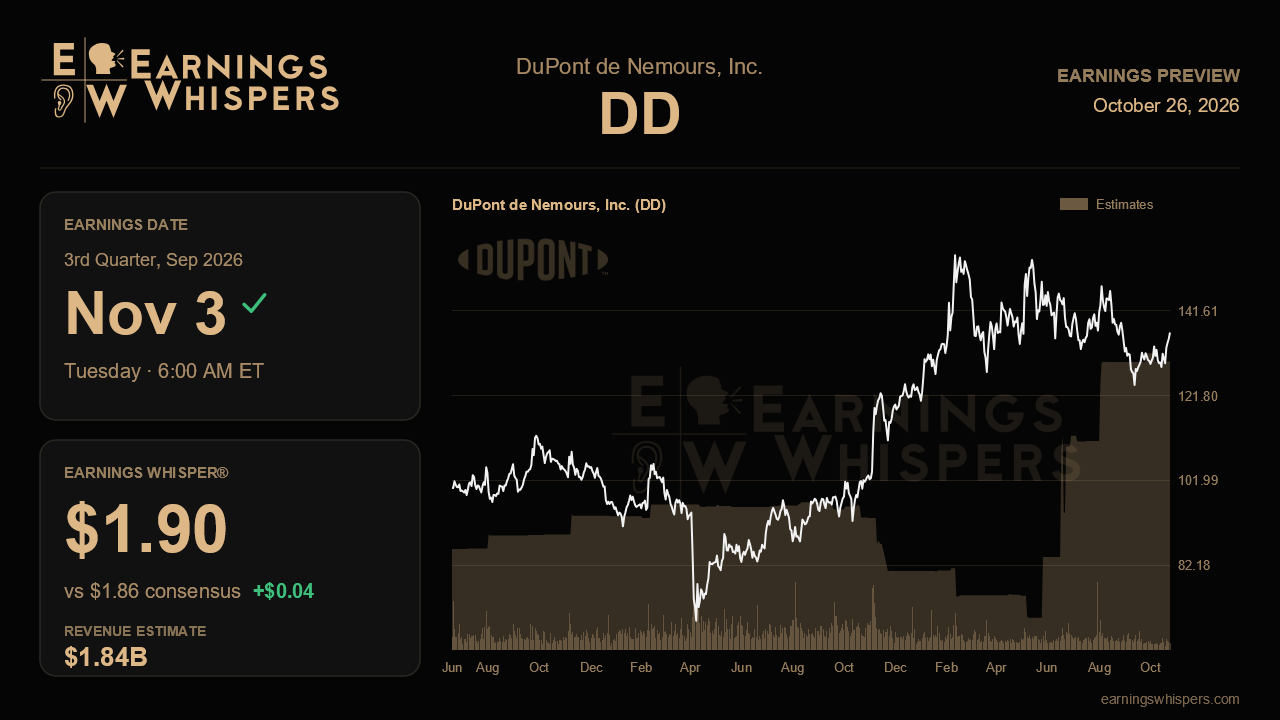
DuPont has turned a reliable pattern into its calling card: beat the quarter, raise the year, repeat. Three straight reports have followed that script, and the company's long campaign to be seen as an industrial compounder rather than a sprawling chemical conglomerate finally earned it a reclassification into the Industrials sector this summer. The third-quarter report, due before the opening bell on November 3, asks a harder question. With guidance already lifted several times, can a slimmer DuPont keep finding upside while its water business stumbles and energy-linked costs bite?
Wall Street expects adjusted earnings of $1.86 a share on revenue of about $1.84 billion. The headline growth figures look jarring, with EPS projected up roughly 71% and revenue down about 40% from a year ago, but those comparisons mostly reflect the separation of the electronics business, the Aramids sale and the June reverse stock split rather than underlying momentum. The more useful benchmark is sequential: the Street is looking for results nearly identical to the $1.88 earned on $1.82 billion in the second quarter. The Earnings Whisper sits a bit higher at $1.90, suggesting the informal bar is modestly above the published one, consistent with a company that has trained investors to expect a cushion.
The full-year setup reinforces that point. Management's latest outlook calls for $7.17 to $7.32 in adjusted EPS on roughly $7.16 billion to $7.19 billion in sales, while consensus sits at $7.16, essentially at or just below the bottom of that range. Revenue expectations line up with the midpoint. In other words, analysts are not fully crediting the last raise, which leaves room for DuPont to clear the quarterly bar if execution holds. The trajectory matters here: organic growth guidance has climbed from about 3% to slightly ahead of 4%, and the EBITDA midpoint has crept up to $1.76 billion. A fourth consecutive raise would signal that self-help is compounding, while a mere reaffirmation could read as the streak running out of steam.
The operational evidence that would validate the story is fairly specific. Healthcare, aerospace, EV battery adhesives and semiconductor ultra-pure water carried the second quarter, and each needs to keep pulling. The 80-20 pilots in four industrial businesses were supposed to begin contributing a few million dollars of EBITDA in the back half, so this is the first quarter where that benefit should start showing up. Net productivity, running near 200 basis points of cost of goods, and free cash flow conversion trending toward 100% are the proof points that justify an industrials-style multiple. On the other side of the ledger, management trimmed its water outlook to low-to-mid single digits because of Middle East desalination delays, flagged a 30 to 50 basis point margin drag from oil and gas inflation that pricing only offsets in dollar terms, and warned of roughly a one-point currency headwind in the quarter. Further slippage in water, or margin erosion in the healthcare and water segment beyond last quarter's 30 basis point dip, would challenge the idea that strength elsewhere can fully absorb the weak spots.
Sentiment has cooled noticeably, slipping to barely bullish from a much warmer reading ahead of the last report, even though the shares have gained about 5% since then while the S&P 500 was flat. That combination suggests investors respect the execution but are skeptical about how much more upside remains. The stock, at about $136.55, sits slightly below its 200-day moving average and in the middle of its post-earnings range, well short of the $149.42 high, so it is not priced for perfection.
The central issue is whether DuPont's self-help engine is strong enough to offset external headwinds without leaning on luck. Steady margins, early 80-20 savings and another nudge higher in guidance would keep the compounding narrative intact. A flat outlook paired with deeper water and cost pressure would suggest the easy raises are behind it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-22 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-30 | |
| Sep-22 | |
| Sep-15 | |
| Sep-11 | |
| Sep-11 |
