DuPont Delivers A Third Beat-And-Raise As Organic Growth Hits 5%, But Water Softness And Price-Led Gains Leave Room For Scrutiny
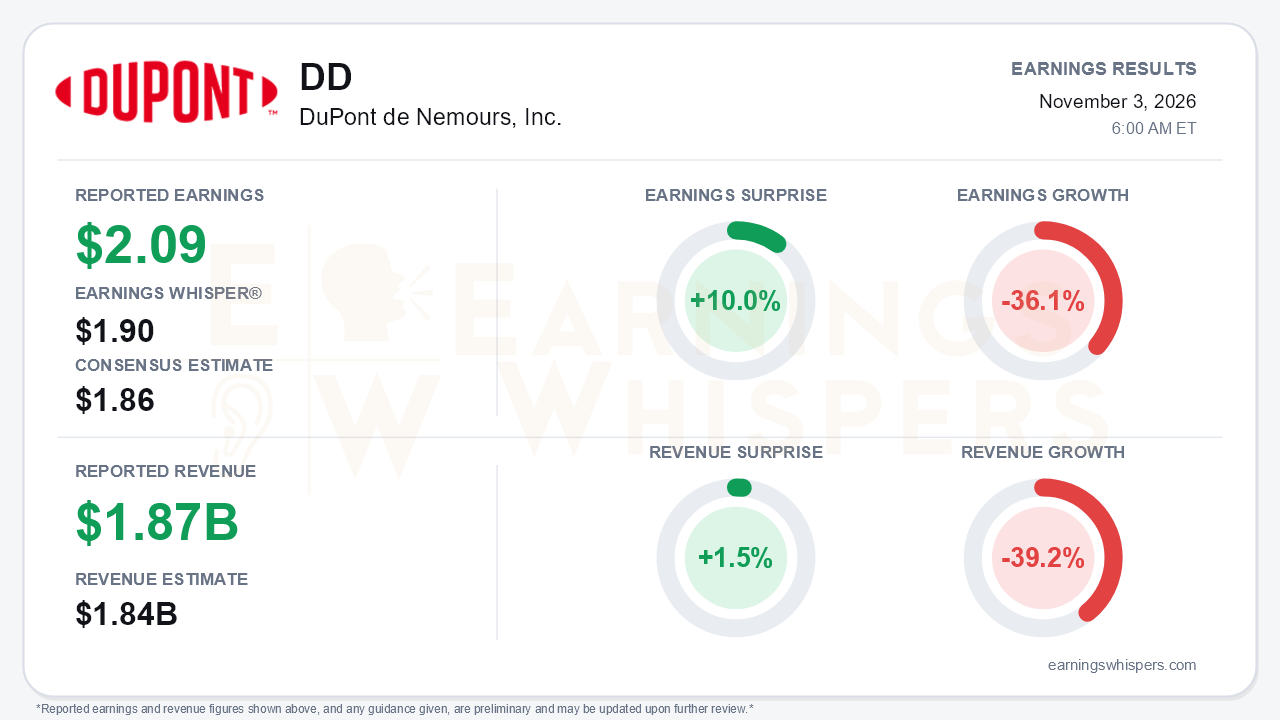
DuPont (NYSE: DD) posted another clean beat in the third quarter. Adjusted EPS was $2.09, versus a $1.86 consensus and a $1.90 Earnings Whisper number, a 10.0% surprise. Revenue of $1.868 billion topped the $1.84 billion consensus by 1.5%. On a normalized basis, earnings fell 36.1% year over year and revenue fell 39.2%. Those declines reflect a reported base that has been reshaped by the November 2025 spin-off of the Electronics business into Qnity and the April 2026 sale of Aramids. On the company's own continuing-operations presentation, the trend runs the other way. Net sales rose 4%, organic sales rose 5%, and adjusted EPS rose from $1.29 to $2.09. Investors should hold both views at once. The headline comparison captures a much smaller company, while the continuing-operations data shows the remaining portfolio is accelerating.
That acceleration is the central takeaway. Organic growth has stepped up from 2% in the first quarter to 4% in the second and 5% in the third. The underlying figure is somewhat better than it looks, because the year-ago quarter in each segment carried a roughly 2% benefit from separation-related order timing. Operating EBITDA rose 8% to $469 million, and margin expanded 80 basis points to 25.1%. Diversified Industrials led the way, with margin up 140 basis points to 24.1%, compared with 22.1% in the second quarter. The quality of the EPS beat still deserves scrutiny. A meaningful share of the 62% adjusted EPS increase came below the operating line:
- Interest expense fell to $40 million from $85 million.
- The diluted share count dropped to 135.1 million from 140.0 million.
- The adjusted tax rate was lower.
GAAP EPS from continuing operations was a more modest $1.24, held back by a $0.31 tax charge. Cash generation was solid but not spectacular. Transaction-adjusted free cash flow of $341 million was essentially flat year over year, although conversion of 121% remains strong.
The call reinforced a credible growth story. Management said the total order book is up double digits. Other demand indicators were also strong:
- Aerospace is growing low double digits with a full order book.
- EV battery sales are up roughly 60% this year.
- Semiconductor-related water is up about 20%.
- Building Technologies is gaining share in a down market.
Net productivity exceeded 2% of cost of goods sold, and on-time-in-full delivery improved for a third straight quarter. Full-year guidance rose for a third consecutive time. The company now expects organic growth of about 4.5%, operating EBITDA of about $1.785 billion, and adjusted EPS of $7.47 to $7.52, all at or above the high end of the prior range. Transaction-adjusted free cash flow conversion is now guided to about 100%. DuPont also added a $250 million fourth-quarter buyback on top of the completed $250 million accelerated repurchase.
Bears still have legitimate ammunition. Water has been trimmed repeatedly. Full-year organic growth for the business was once expected in the mid-single digits and is now about 1%, after roughly $15 million of Middle East desalination revenue slipped into 2027. Pricing assumptions climbed to about $110 million from $90 million, but that pricing is largely surcharge-based and offsets oil and gas inflation. Growth of that kind could reverse if raw material costs ease. Construction and automotive, roughly 40% of the portfolio, are still declining low single digits. Early 2027 commentary pointed to end markets similar to 2026 rather than a broad recovery. Earnings Whispers characterized the guidance as mixed, and the fourth-quarter outlook explains why. Adjusted EPS of $1.90 to $1.95 and EBITDA of about $455 million both step down sequentially, and management flagged lower Diversified Industrials margins. That softer near-term profile comes even as the implied fourth-quarter organic growth of about 8% looks strong.
The market setup is more complicated than the surprise implies. Investor sentiment remained positive heading into the report but weakened substantially, falling from 0.36 to 0.13. Shares closed at $141.30 the day before the release, up 8.5% from the open following the August report and about 2.1% above the 200-day moving average. They had not recovered the $149.42 high set two days after that report and sat 5.4% below it. The stock had rebounded 15.1% from its September 14 low of $122.80. The Earnings Whispers trend signals are mixed. Momentum and AVWAP readings are positive, while sequential growth and price trend readings are negative. That split fits a stock whose expectations cooled even as the business kept outperforming.
The bottom line is that DuPont is executing well on the operating metrics it controls. Organic growth, margins, productivity, and capital returns are all improving, and the guide keeps moving higher. The headline growth figures remain distorted by portfolio changes, and part of the EPS gain came from interest, tax, and buybacks rather than operations. Price-led growth, a stalled water business, and a sequential fourth-quarter step-down mean the quarter supports the improvement narrative without fully settling the debate over how durable it is.
Read our earnings preview for DuPont de Nemours, Inc.: https://www.earningswhispers.com/article/DD/21472
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 6 hours | |
| 6 hours | |
| 6 hours | |
| Oct-29 | |
| Oct-26 | |
| Oct-22 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-09 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 |
