Zebra's Street Bar Sits Above Its Own Guidance As Memory Costs Test The Margin Story
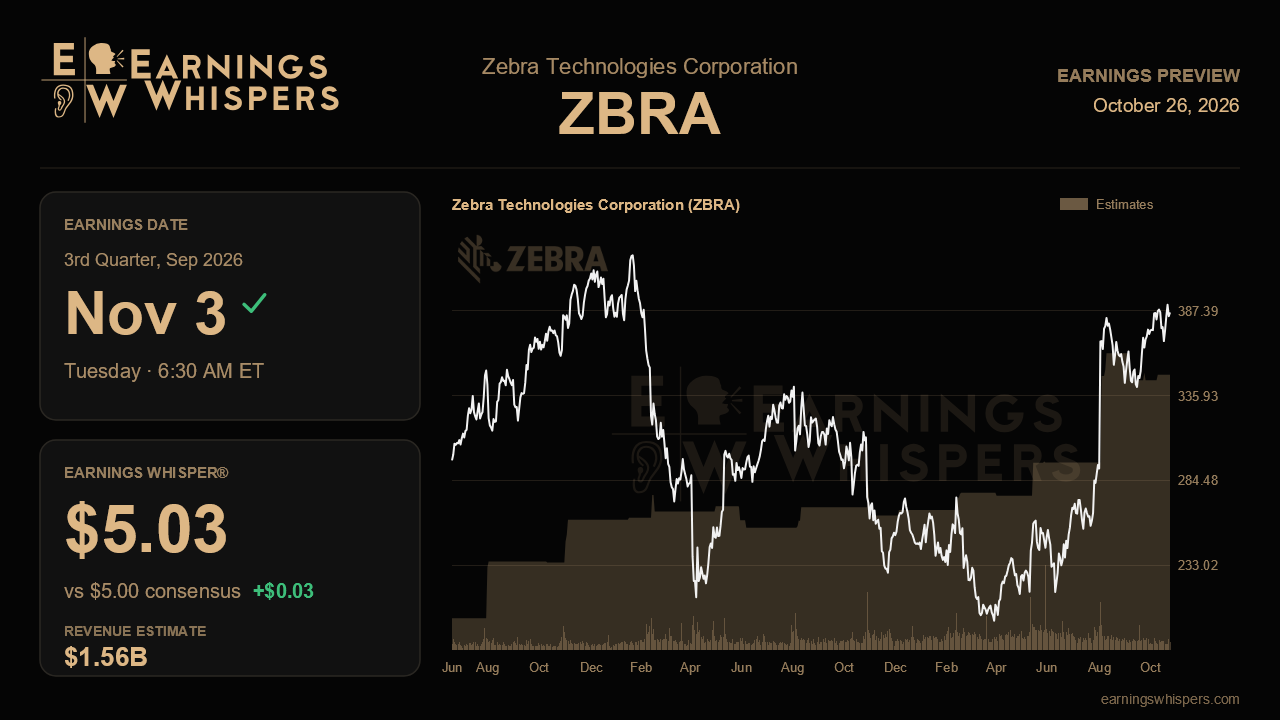
Zebra Technologies heads into its third-quarter report with an unusual setup. Management just raised its full-year outlook for the third straight quarter, the stock has run well ahead of the market, and Wall Street is now asking for more than the company itself promised. The question for the November 3 release, due before the open, is whether Zebra's demand momentum is strong enough to clear a bar that analysts have quietly lifted above the guidance range, even as tariff recoveries fade and memory costs bite.
Consensus calls for non-GAAP earnings of $5.00 per share on revenue of about $1.56 billion. Revenue would be up roughly 18% from a year ago, and earnings would be up about 72% from the $2.90 posted in the year-ago quarter. Revenue expectations sit squarely at the midpoint of management's $1.54 billion to $1.58 billion range, but the earnings estimate is above the top of the company's $4.70 to $4.90 guidance. The whisper number of $5.03 is only marginally higher, so it does not signal a dramatically different view, but it confirms that the market expects another upside surprise rather than a guidance-matching quarter. Keep in mind that much of the headline revenue growth reflects acquisitions such as ELO. Organic growth ran about 9% last quarter, and that underlying figure is the better gauge of demand.
The prior call gave investors plenty of reasons for confidence. Zebra lifted its full-year organic growth outlook to 14% to 16%, up from 10% to 14% a quarter earlier and 9% to 13% at the start of the year. Full-year EPS guidance jumped to $20.75 to $21.25, the adjusted EBITDA margin target rose to 23.5% to 24%, and free cash flow guidance moved to at least $1 billion. Demand was broad, with double-digit growth in retail, manufacturing and healthcare, and the turnaround in manufacturing and machine vision was especially notable given how soft that business looked a year ago. Validation this quarter means seeing those end markets hold their pace, healthcare remain a leading grower, and early evidence that ELO synergies and the new AI-enabled devices with embedded RFID are contributing.
The complication is margins. Management guided third-quarter EBITDA margin to roughly 22%, a steep sequential drop from last quarter's 27.7%, as a large tariff recovery falls away and memory costs rise about a point. Zebra says it has offset most of an estimated $120 million memory headwind through $90 million of price increases plus productivity and currency benefits. Beating the EPS consensus will likely require margins to land above that 22% marker, which would show pricing is sticking without denting volume. A margin result at or below guidance would raise questions about whether further price hikes are needed and whether customers will absorb them. Commentary on memory supply also matters, because management has said fourth-quarter revenue, implied at around 8% organic growth, is constrained by component availability rather than demand.
Expectations have clearly warmed. Sentiment has climbed to modestly bullish from nearly neutral before the last report, and the stock is up about 17% since then while the S&P 500 has been flat. At around $386, shares trade far above their 200-day average and within 2% of the post-earnings high near $393, effectively testing a breakout. That leaves less room for a merely in-line print.
Ultimately, this report hinges on whether Zebra can show that pricing power and broad demand are outrunning memory inflation. A beat paired with reassurance on fourth-quarter supply, steady EMEA trends and a growing transportation and logistics refresh pipeline for 2027 would keep the upward revision cycle intact. Anything suggesting memory is limiting both margins and shipments would challenge the story the stock has already priced in.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 |
AI Stock Catapults 58% Amid Robotics Business Spinoff; Nears Pivot As Earnings Loom
ZBRA
Investor's Business Daily
|
| Oct-26 | |
| Oct-26 | |
| Oct-10 | |
| Oct-06 | |
| Oct-05 | |
| Sep-25 |
This Physical AI Stock Finds Support, Eyes New Entry As Earnings Gallop 76% Higher
ZBRA
Investor's Business Daily
|
| Sep-23 | |
| Sep-18 | |
| Sep-17 | |
| Sep-14 | |
| Sep-02 | |
| Sep-02 | |
| Aug-31 | |
| Aug-20 |
