Zebra Misses The Street By A Nickel As Accelerating Demand Runs Into A Memory-Cost Squeeze
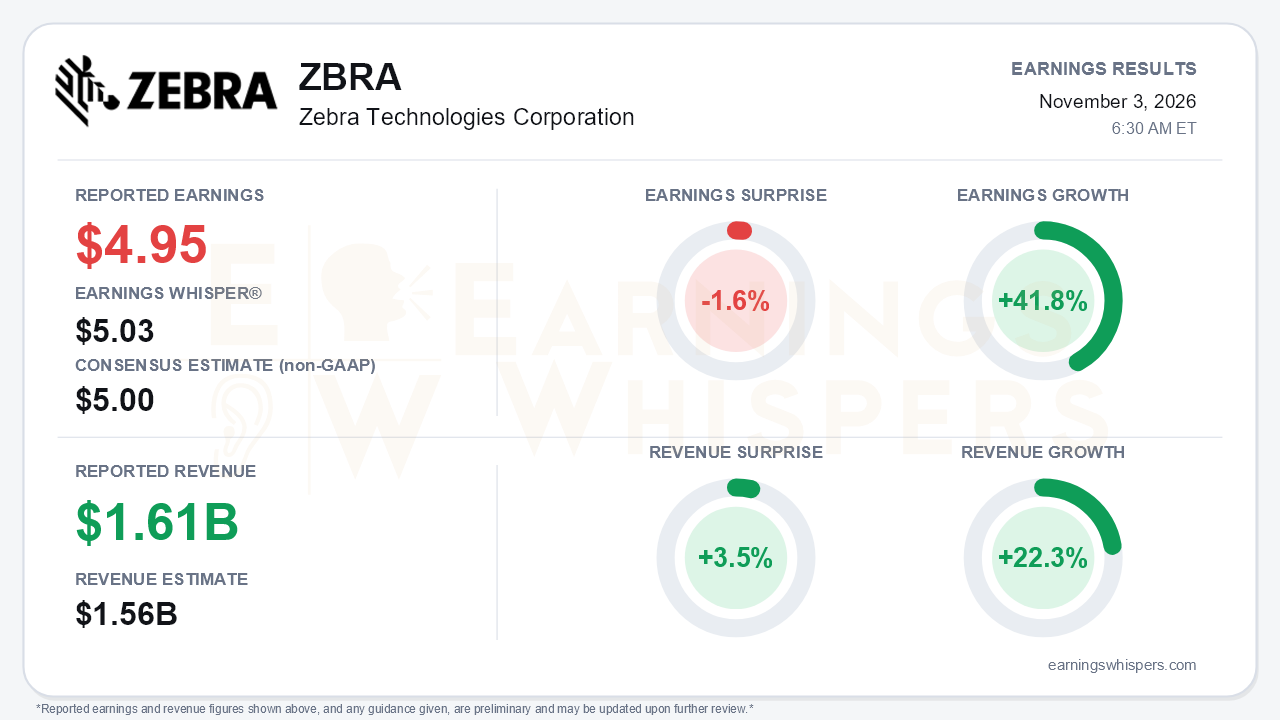
Zebra Technologies delivered a quarter in which the top line and the bottom line told different stories. Third-quarter non-GAAP EPS of $4.95 missed the $5.00 consensus by 1.6% and fell short of the $5.03 Earnings Whisper number. Revenue of $1.614 billion, meanwhile, beat the $1.56 billion consensus by 3.5% and grew 22.3% year over year. Earnings grew 41.8% on Earnings Whispers' normalized basis. Measured against the company's own reported prior-year non-GAAP figure of $3.88, the gain was 27.6%, which suggests a difference in prior-year comparison basis. The miss is also relative. EPS cleared management's $4.70-$4.90 guidance, so the shortfall reflects a Street bar that had moved above the company's own outlook. That is the central tension: demand is clearly accelerating, but memory costs are absorbing a growing share of the upside.
The quality of the revenue beat is better than the headline growth rate alone implies, even after adjusting for acquisitions. Elo Touch contributed 8.9 points of reported growth and currency added 2.1 points, leaving organic growth at 11.3%. That figure has risen on every recent report: 2.5% in the fourth quarter of 2025, 4.3% in the first quarter, 9.2% in the second, and 11.3% now. Connected Frontline grew 15% organically and Asset Visibility & Automation grew 7%. Gross margin is where the quarter weakens. Adjusted gross margin fell 220 basis points to 46.0%, down from 53.3% in the tariff-aided second quarter and 50.4% in the first. Adjusted EBITDA margin held flat at 21.6% only because operating leverage offset the gross-margin erosion. GAAP EPS of $3.43, up from $1.97, also benefited from a sharply lower tax expense: $34 million versus $58 million a year ago.
The call sharpened both sides of the story. Memory costs rose more than $50 million year over year in the quarter, and pricing recovered only about half of that. Management raised its full-year memory headwind estimate to roughly $145 million from about $120 million, citing higher mobile computing volume. The pressure is now spreading beyond mobile computers into AVA, where memory reduced margins by about 2.5 points. Memory prices are expected to keep rising into the first half of 2027, and management did not quantify next year's cost impact. Full-year adjusted EBITDA margin guidance settled at about 23.5%, the low end of the prior range.
On demand, however, the evidence was strong. Every region grew, and EMEA accelerated to 13% from 7% in the second quarter. Transportation and logistics swung from flat to the fastest-growing end market, with multi-year global refresh rollouts slated to begin in 2027. A large North American specialty retailer is deploying Zebra's AI Companion across all of its locations. Management also said it sees no demand pull-forward. The full-year outlook rose again, to roughly 17% sales growth and about $21.20 in non-GAAP EPS, compared with February's 9%-13% and $17.70-$18.30. For the first time, management framed 2027 growth at the high end of its 5%-7% long-term range, supported by a roughly 15% October price increase on mobile computers that is expected to add about 1.5 points. Fourth-quarter guidance calls for 10%-14% growth, including about 150 basis points from currency, with EPS of $5.00-$5.40 and EBITDA margin near 22%. That margin is the baseline management set for 2027. Reported growth will slow as Elo laps its acquisition anniversary.
The balance sheet deserves attention. Year-to-date free cash flow reached $661 million, and the at-least-$1 billion full-year target was reaffirmed. Working capital is absorbing cash, though: receivables and inventories have climbed, partly from deliberate memory stockpiling to secure 2027 supply. With $2.08 billion of debt now classified as current ahead of a credit facility that matures in May 2027, refinancing is a near-term task. Buybacks slowed to $75 million in the third quarter from $568 million in the first half. Customer pushback on successive price increases is another risk bears can reasonably cite.
Investors entered the report with sentiment slightly more positive than after the prior quarter, though still close to neutral. Shares rose 9.4% from the open after the August report to $361.13. That leaves them roughly 29% above the 200-day moving average but about 8% below the October 21 52-week high of $392.78. Most Earnings Whispers trend readings are positive, while AVWAP remains negative, consistent with a stock that has pulled back from its recent peak.
The bottom line is that Zebra's growth engine is running faster than at any point in the past year, and the guidance path keeps moving higher. Memory inflation, however, has turned margin expansion into margin defense. The modest EPS miss matters less than whether pricing can close the cost gap before 2027 margins are locked in at the fourth-quarter baseline.
Read our earnings preview for Zebra Technologies Corporation: https://www.earningswhispers.com/article/ZBRA/21536
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 8 hours | |
| 11 hours | |
| 14 hours | |
| 14 hours |
Zebra Technologies Delivers Q3 Earnings Beat, Raised Outlook, But Stock Falls
ZBRA -8.76%
Investor's Business Daily
|
| 14 hours | |
| 16 hours | |
| Oct-27 |
AI Stock Catapults 58% Amid Robotics Business Spinoff; Nears Pivot As Earnings Loom
ZBRA
Investor's Business Daily
|
| Oct-26 | |
| Oct-26 | |
| Oct-10 | |
| Oct-06 | |
| Oct-05 | |
| Sep-25 |
This Physical AI Stock Finds Support, Eyes New Entry As Earnings Gallop 76% Higher
ZBRA
Investor's Business Daily
|
| Sep-23 |
