Wayfair's Raised Growth Guide Faces Its First Test As Street Eyes Low End
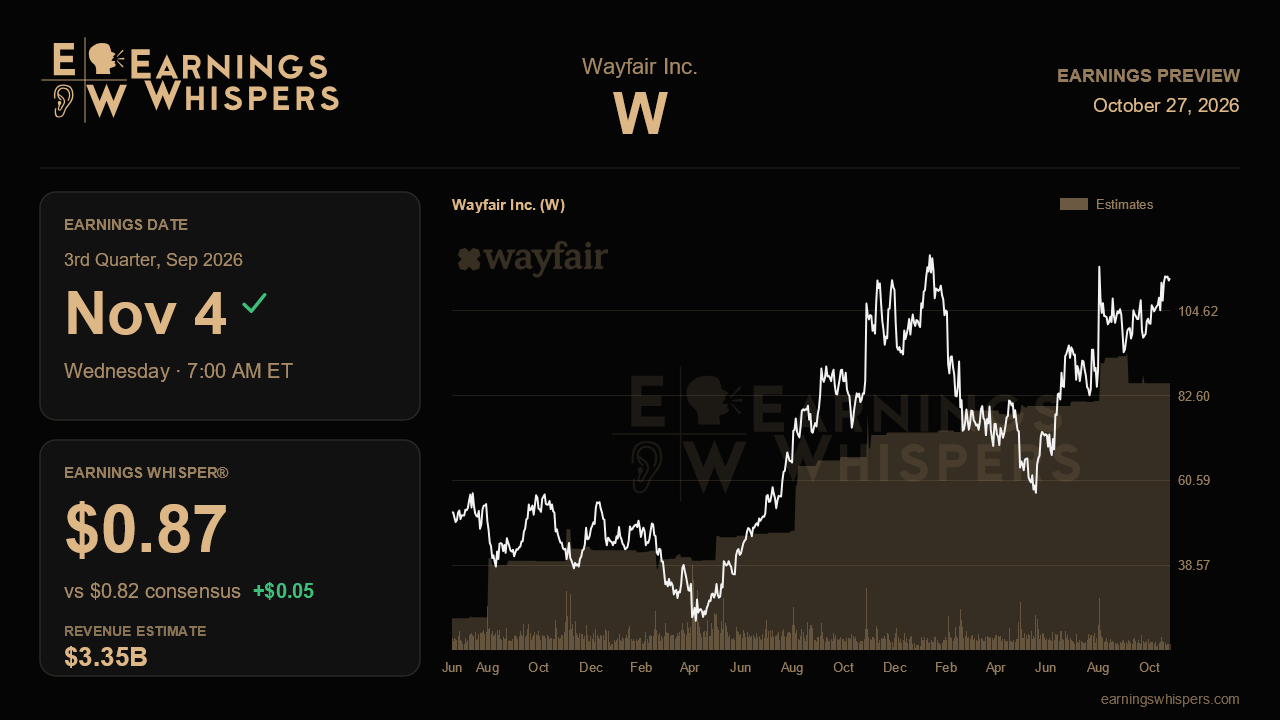
Wayfair spent much of the post-pandemic period guiding cautiously, so when management lifted its outlook to high single-digit revenue growth for the third quarter, it was the first step-up in more than a year. The report due before the open on November 4 will show whether that confidence was earned or merely well timed. The stock has more than doubled off its lows from earlier in the year. That leaves the company needing to show the acceleration is durable, not just to post a respectable quarter.
Wall Street expects non-GAAP earnings of $0.82 per share on revenue of about $3.35 billion. That revenue figure implies growth of roughly 7.5%, which sits at the low end of what most would call high single digits. Analysts, in other words, are taking management at its word without stretching. The Earnings Whisper of $0.87 is a bit above consensus, a sign that the more engaged crowd expects some upside. The profit comparison is stark: a year ago Wayfair earned just a penny on an adjusted basis, so the story here is margin leverage on modest top-line gains rather than explosive demand.
The core of the bull case is the US business. Domestic revenue grew 8.7% last quarter, the best of the post-COVID era, and order growth doubled to 6%. New-order growth improved for a fourth straight quarter. To validate the guide, the US needs to hold or extend that pace, ideally with orders continuing to grow faster than revenue. That would show customer acquisition, not price or mix, is doing the work. Active customer growth of better than 3% is another metric to track. A stall there would suggest the loyalty program is mainly rewarding existing shoppers. Management also flagged that the US home category had turned roughly flat to slightly positive for the first time since 2021. With guidance assuming no help from housing turnover, any sign the category slipped back would put more pressure on share gains.
The weak link is international. The segment swung to a 1.3% decline last quarter after growing 6% the quarter before. Management blamed timing, noting loyalty only recently launched abroad. A second negative print would make that explanation harder to accept, while a return to growth would neatly support it. Gross margin is the other swing factor. Management steered toward the low end of its 29.5% to 30.5% range as it reinvests in loyalty and service. It argued advertising savings offset that roughly one for one, keeping contribution margin near 15.3%. If gross margin dips below the range or contribution margin erodes, the reinvestment starts to look less self-funding.
Newer catalysts deserve a progress check as well. Paragold, the luxury franchise, was disclosed at a run-rate above $400 million and growing faster than 35%. Any update on new stores or the planned Paragold loyalty program would help gauge whether the multibillion-dollar ambition is credible. Investors should also want early detail on the shift to outright buybacks to offset stock-based compensation, a notable change for a company long focused on paying down convertible debt.
Sentiment has warmed only slightly since the last report, and the stock has outpaced the S&P 500 by about two percentage points over that stretch. Shares trade well above their 200-day moving average and sit about 4% below the post-earnings high of $118.31. That positioning reflects optimism without euphoria. The central question is simple: can US growth keep accelerating while gross margin holds near 30%? If both happen, the path management sketched toward much faster organic growth looks more believable. If either cracks, last quarter's guidance raise will look more like a peak than a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-15 | |
| Oct-15 |
UK watchdog fines Wayfair and Appliances Direct over misleading sales
W +6.82%
Retail Insight Network
|
| Oct-14 | |
| Oct-10 | |
| Oct-01 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-23 | |
| Sep-21 | |
| Sep-21 | |
| Sep-18 | |
| Sep-17 | |
| Sep-16 |
