Coeur Mining's Q3 Puts Its Canadian Ramp-Up And Second-Half Cash Promise On Trial
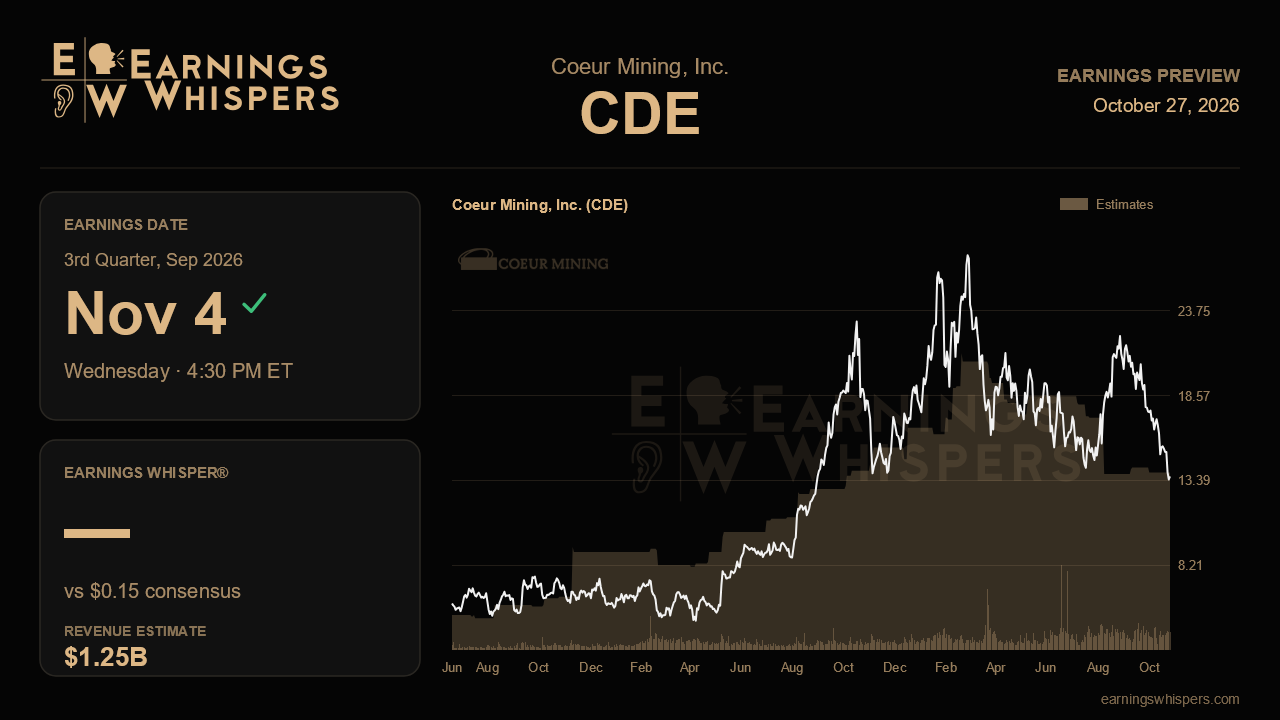
Coeur Mining heads into its third-quarter report with a stock that has been marked down hard and a business that management insists is about to hit its stride. Since the last report, shares have fallen nearly 15% while the S&P 500 was essentially flat, even though the company had just posted record revenue, record free cash flow and its first $1 billion cash balance. The disconnect traces back to one issue: the newly acquired New Afton and Rainy River mines were guided lower for the second time in a few months, and the company's full-year story now depends heavily on a second half that has not yet been delivered.
Wall Street expects earnings of $0.15 per share on revenue of about $1.25 billion when results arrive after the close on November 4. Revenue would more than double from the $554.6 million reported a year ago, reflecting the far larger asset base, and would mark a solid step up from the $1.09 billion posted last quarter. Earnings per share, however, are projected to fall roughly 35% from $0.23 a year earlier. That gap between top-line growth and per-share profit is worth understanding: this is a much bigger, more heavily capitalized company, and acquisition accounting effects, such as the $141 million inventory fair-value uplift that weighed on the second quarter, can distort reported earnings even when cash generation is strong. Free cash flow is likely the cleaner scorecard.
On that front, the math is demanding. Management framed full-year 2026 at roughly $2.3 billion of EBITDA and $1.5 billion of free cash flow. With about $655 million generated across the first two quarters, the back half needs to produce something in the neighborhood of $845 million, or about $420 million per quarter, above the record $388 million from the second quarter. A third-quarter figure at or above that pace would go a long way toward validating the plan. A shortfall would push even more of the burden into the fourth quarter, which is exactly the concentration risk skeptics flagged.
The operational checkpoints are specific. New Afton was running around 14,000 tonnes per day in late July against a 16,000 tonne target now set for early in the fourth quarter, so this report should show whether the cave draw is trending toward that goal or slipping again. Rainy River's underground output had climbed about 40% to roughly 3,300 tonnes per day after contractor problems, with 5,000 tonnes targeted by year-end; continued progress there would ease concerns about the extra $30 million of operating costs and higher capital tied to the fix. A third reset at either mine would seriously damage confidence in the acquisition's execution. On the legacy side, Rochester's Phase 2A leach pad and record crushing rates were meant to set up a sharp rise in silver output, and grades at Kensington, Rochester and Palmarejo, which came in light in the second quarter, are supposed to rebound. Diesel inflation and lower assumed realized prices are the cost and pricing swing factors to monitor.
Sentiment has softened its bearish edge slightly, improving to a modestly negative reading from a more pessimistic one ahead of the last report, but the price action tells a gloomier story. At $13.64, the stock sits well below its 200-day moving average of $19.05 and only about 4% above its post-earnings low of $13.12, a long way from the $22.45 high. That positioning suggests the market has already priced in meaningful skepticism, which lowers the bar somewhat if the Canadian numbers cooperate. Updates on the $750 million buyback, of which $110 million had been used through June, will also signal how management views its own valuation.
Ultimately, this report hinges on whether New Afton and Rainy River are finally tracking the revised plan. If they are, and cash flow keeps pace with the second-half target, the recent selloff looks like an overreaction. If not, the full-year framework itself comes into question.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-14 | |
| Oct-09 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-21 | |
| Sep-17 | |
| Sep-16 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 | |
| Aug-14 | |
| Aug-13 | |
| Aug-10 |
