Coeur Mining Matches On EPS But Misses On Revenue As Outlook Slips Again And The Year Hinges On A Steep Fourth Quarter
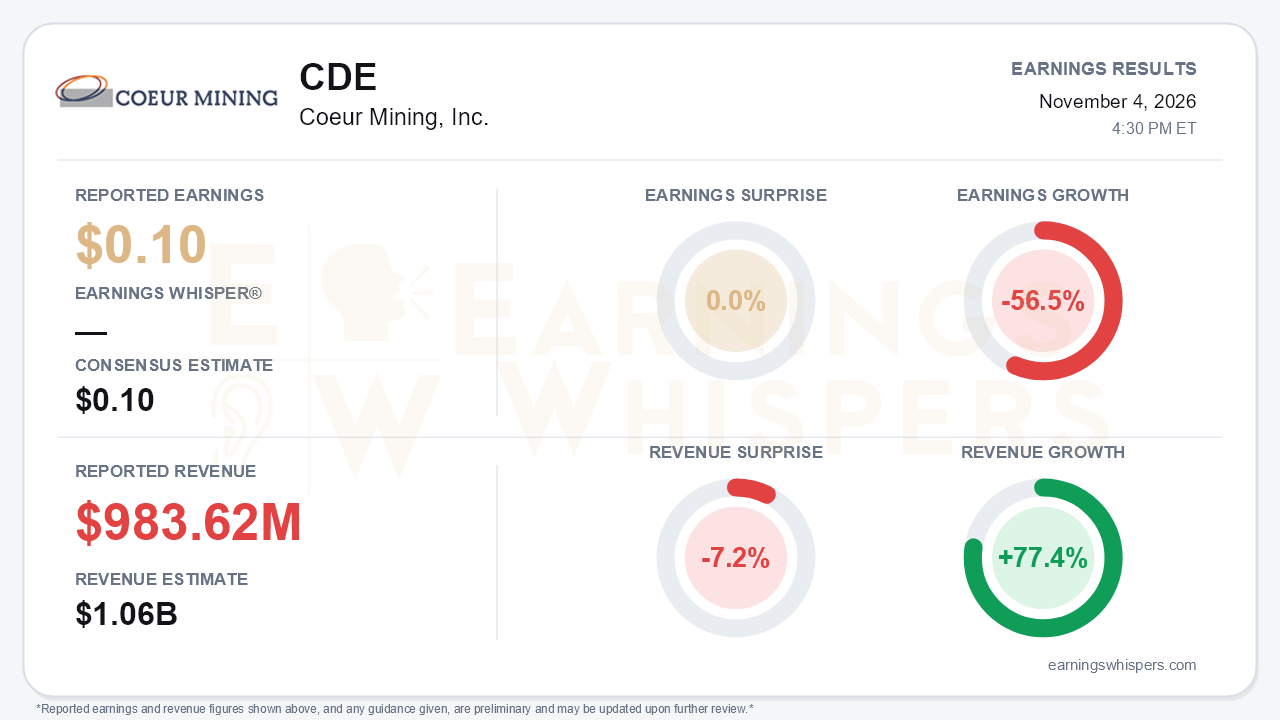
Coeur Mining delivered adjusted earnings of $0.10 per share for the third quarter, exactly matching the consensus estimate. That in-line result is the least important part of the report. Revenue of $983.6 million missed consensus by 7.2%, adjusted EPS fell 56.5% year over year despite 77.4% revenue growth, and management cut its full-year cash-generation outlook for the second straight quarter. It also now expects gold, silver and copper production at the low end of guidance. That is the central tension: the acquisition-enlarged company is generating far more cash than a year ago and the balance sheet keeps getting stronger, yet the operating plan keeps drifting lower and the remaining year depends on a demanding fourth quarter.
The headline growth comparisons are almost entirely acquisition-driven, and per-share earnings tell a less flattering story. Weighted average shares rose to 1.03 billion from 645 million a year ago after the New Gold transaction. As a result, a 69% jump in adjusted EBITDA to $448 million did not translate into per-share growth. The sequential trend is the bigger concern. Adjusted EPS has slid from $0.36 in the first quarter to $0.12 in the second and $0.10 now. Revenue declined from $1.09 billion in the second quarter as realized gold fell to $3,979 an ounce and silver dropped to $62.22. GAAP EPS was $0.11. Both GAAP and adjusted results absorbed $40 million, or $0.03 per share, of non-cash purchase-accounting expense on Rainy River stockpile inventory. Free cash flow of $240 million was well below the second quarter's record $388 million, and operating cash flow fell 25% sequentially, including about $50 million of working-capital outflows.
Beneath the totals, the quarter was a patchwork of setbacks:
- **New Afton:** a conveyor failure cut throughput.
- **Rainy River:** heavy rain forced more low-grade stockpile processing, and grade fell to 0.77 g/t from 0.90.
- **Palmarejo:** rain disrupted backfill and access to higher-grade areas, pushing silver grade down to 89 g/t from 119 a year ago.
- **Rochester:** silver leaching was slower than expected as sulphide ore showed up more sharply than modeled.
- **Costs:** the call flagged diesel running 32% above plan, roughly $30 million of added cost, along with broader inflation in labor, consumables and contractors.
There were genuine bright spots. Rochester gold rose 39% sequentially on record crushing, and Wharf gold climbed 28%. Rainy River underground rates improved to about 3,400 tonnes per day from 2,300, and New Afton reached its 16,000-tonnes-per-day mining target after repairs. Adjusted EBITDA margin edged up to 46% from 44%, and gold unit costs fell 16% sequentially. However, that cost improvement mostly reflects the shrinking purchase-accounting charge rather than cheaper mining.
The guidance changes carry the most weight. Management now targets about $2 billion-plus of adjusted EBITDA and free cash flow exceeding $1.3 billion at current prices. Free cash flow was framed near $1.5 billion last quarter and about $2 billion in the first quarter, and EBITDA was guided above $3 billion at budget prices earlier in the year. Some of that erosion is price-driven, but not all. On the second-quarter call, the legacy mines were described as on track, and now the whole portfolio sits at the low end with costs at the upper end of guidance. Hitting even the low end requires roughly a 29% sequential step-up in gold and 36% in silver, which analysts questioned directly. Sustained 5,000-tonne-per-day underground output at Rainy River has also slipped toward the second half of 2027.
Management's tone cooled noticeably. The call acknowledged a "lighter than expected" quarter, a contrast with the enthusiasm of three months ago, and M&A is explicitly on hold while the team digests and delivers.
The counterweights are real. Cash reached $1.17 billion with net cash of $471 million. Buybacks totaled $111 million in the quarter, about 46% of free cash flow, and $231 million since mid-May. A second $0.02 dividend was declared, and a $70 million Wharf insurance payment is due in the fourth quarter. With the Rainy River inventory step-up largely run off, reported costs should look cleaner from here. Management continues to frame 2027 as another record year on a full year of Canadian contributions.
Investors were not leaning bullish going in, and the setup darkened modestly. Earnings Whispers sentiment slipped to -0.108 from -0.088, a small move that leaves expectations slightly more negative. Shares at $14.58 are down 8.9% since the open after the August report and sit 22.5% below the 200-day moving average of $18.81. Price and AVWAP trend readings remain negative. The market has clearly been discounting execution risk well before this report.
The bottom line is that Coeur's quarter was more about credibility than earnings. The EPS match and the rising cash pile show a business throwing off substantial free cash, but repeated outlook cuts, low-end production targets and a back-end-loaded fourth quarter give bears legitimate ammunition. Until Coeur demonstrates that the Canadian ramp-ups and legacy mines can hit plan without weather, equipment or cost excuses, the strengthening balance sheet is likely to be weighed against an operating story that keeps resetting lower.
Read our earnings preview for Coeur Mining, Inc.: https://www.earningswhispers.com/article/CDE/21800
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-14 | |
| Oct-09 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-21 | |
| Sep-17 | |
| Sep-16 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 |
