U.S. Physical Therapy Must Prove Its Second-Quarter Margin Squeeze Was Temporary
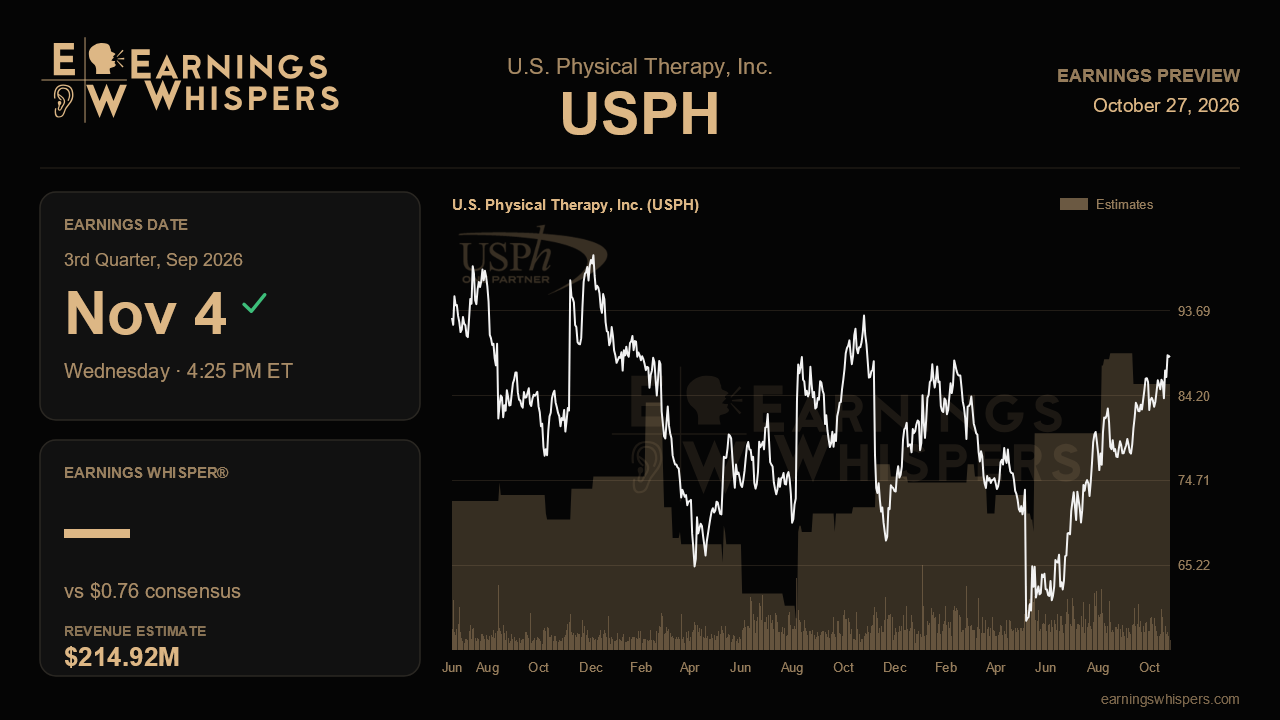
U.S. Physical Therapy enters its third-quarter report with a stock that has run well ahead of the evidence. Shares have climbed 17.3% since the last report while the S&P 500 slipped, yet the quarter that set off the rally was mixed. Demand and pricing hit records, but gross margins fell sharply. Management called the second quarter a trough and kept full-year guidance unchanged rather than raising it. The November 4 release, due after the close, is the first real test of that trough claim.
The Street expects earnings of $0.76 per share on revenue of $214.9 million. That would be 15.2% EPS growth and 9.0% revenue growth from a year ago, a solid clip for a clinic operator. The sequential picture is flatter. Revenue would rise less than $1 million from the second quarter's $214.1 million, and EPS would edge up from $0.75 in adjusted operating results. That modest step-up is notable, because management's reaffirmed adjusted EBITDA target of $102 million to $106 million relies on the hospital ramp lifting the back half. Consensus does not seem to demand a dramatic rebound. A clear third-quarter improvement would make the upper half of the range look reachable. Results near the second-quarter run rate would push attention toward the low end.
Margins are the main swing factor. Adjusted PT gross margin dropped to 19.9% from 21.4% a year earlier, and management blamed two items it described as temporary. The first was self-insured employee medical claims running about $3.2 million above last year, with roughly 80% of that excess landing in the second quarter. The second was more than $2 million of front-loaded costs from pre-hiring about 50 clinicians and setting up hospital partnerships before reimbursement began. If claims revert toward normal and those new clinicians are now seeing patients, margins should recover visibly. Salaries rose to 57.5% of revenue last quarter, so that ratio will show whether the hiring has started to pay for itself. Another quarter of compression would challenge the claim that the pressure was transitory.
The hospital strategy carries the longer-term story. Affiliations added $5.6 million of revenue in the second quarter, and the NYU Langone metro transition was slated to bring all 60 clinics on board by the end of August. Management also raised its 2027 view, saying hospital EBITDA should exceed the earlier $7.3 million base case. This report should give the first near-full quarter with that footprint in place. Look for evidence that volume and contribution are building on schedule, not just cost.
The core operating metrics set a high bar. Visits per clinic per day reached a record 33.5 and net rate per visit hit a best-ever $107.59, while mature-clinic revenue growth sped up to 3.5%. Holding those levels against a year-ago comparison of 32.2 visits would confirm that demand is durable. Two areas need repair. Organic growth in the industrial injury prevention business slowed to 3.6% after losing a Japanese auto contract and leaving positions unfilled. Debt also rose to $221 million to fund acquisitions, which lifted interest expense, so recent deals now need to visibly add earnings.
Sentiment has drifted slightly more bearish than before the last report, an odd mix with a stock trading at $88.65. That price sits well above its 200-day average of $76.74 and within about 1.5% of its post-earnings high of $89.98, so it is testing a breakout. With the shares priced for recovery, the outcome hinges on one point. U.S. Physical Therapy needs to show that its record volumes and rates are finally reaching the margin line as medical claims and transition costs fade. That would support the 2027 acceleration management described. Without it, the reaffirmed guidance starts to look like a ceiling rather than a floor.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-21 | |
| Sep-21 | |
| Aug-27 | |
| Aug-14 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-02 | |
| May-14 | |
| May-06 | |
| May-06 | |
| Apr-27 | |
| Apr-22 |
