U.S. Physical Therapy Beats As Hospital Affiliations Drive Growth Acceleration, But Unchanged Guidance And Rising Costs Keep Investors Wary
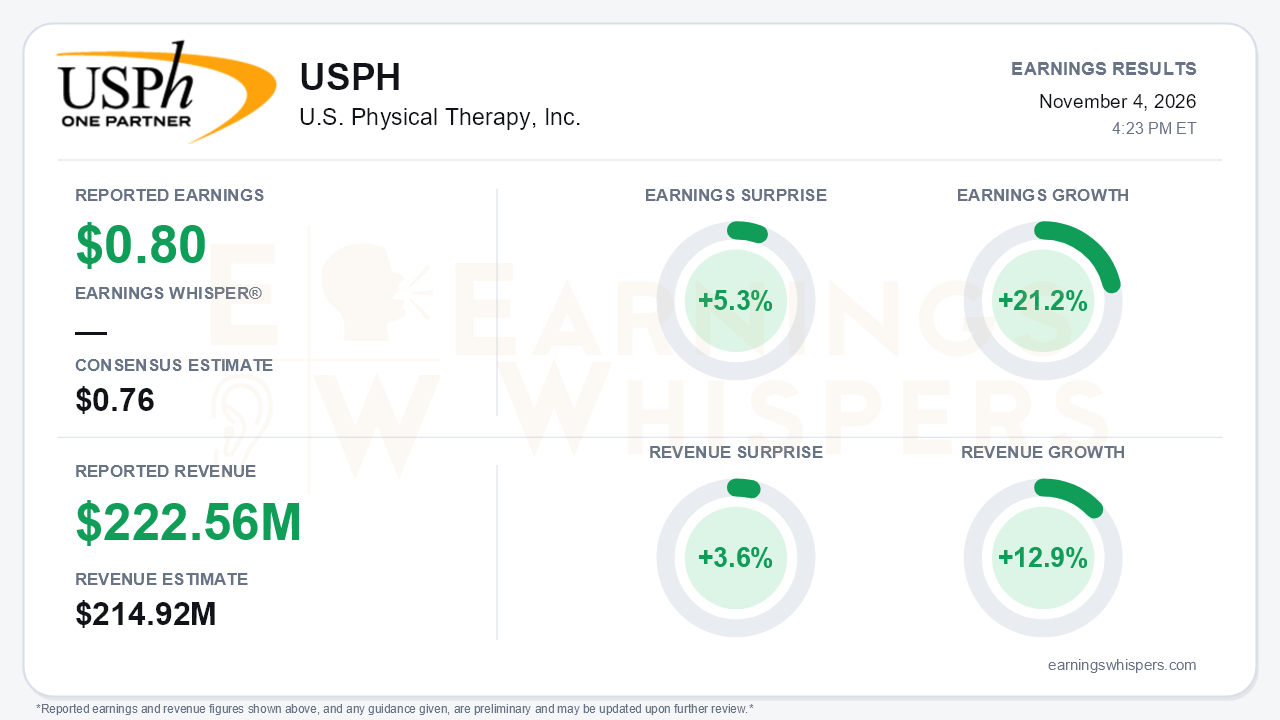
U.S. Physical Therapy delivered its strongest quarter of the year, and the improvement came from accelerating growth rather than cost-cutting. Adjusted EPS of $0.80 beat the $0.76 consensus by 5.3% and grew 21.2% year over year. Revenue of $222.56 million topped the $214.92 million estimate by 3.6% and rose 12.9%. The trajectory matters more than the beat. Revenue growth stepped up from roughly 7.9% in Q1 and 8.5% in Q2 to 13% in Q3. Adjusted EPS swung from a decline in Q2 ($0.75 vs. $0.81) to solid growth. The central tension is that management reaffirmed full-year adjusted EBITDA guidance of $102 million to $106 million for a fourth straight call, despite the visible acceleration.
The headline growth deserves some unpacking. The newly completed hospital affiliations contributed $25.0 million of revenue, up from $5.6 million in Q2, and now account for more than 13% of the total. Excluding that new line, net patient revenue slipped 1.8% to $161.1 million. Still, the organic signals were real:
- Mature clinic revenue rose 6.4%, up from 3.5% in Q2 and 2.5% in Q1.
- Visits grew 8%.
- Net rate per visit hit a record $111, up $5, with September at $112.
GAAP results look very different. The company reported a loss of $1.04 per share. That loss was driven by a $36.2 million revaluation of redeemable non-controlling interests charged against retained earnings. This is an accounting effect of partner stakes becoming more valuable, not an operating loss. GAAP net income attributable to shareholders was $11.0 million, down from $13.1 million, mostly because last year's quarter included a $5.9 million earn-out gain.
Margins improved despite a meaningful cost headwind. Self-insured employee health claims ran $7 million above the prior year through nine months, up from $3.2 million as of Q2. Those claims cost roughly 150 basis points of physical therapy margin in the quarter. Even so, adjusted PT margin reached 19.1% versus 18.5% a year earlier. The release text describes this as a gain of about 150 basis points, but the segment table supports roughly 60 basis points. The industrial injury prevention (IIP) segment performed well:
- Margin expanded to 21.9% from 19.6%.
- Revenue grew 14%, or 8% excluding the January acquisition.
- Workers' comp revenue per visit rose 8%.
Adjusted EBITDA increased 16% to $27.8 million, after a flat Q2. Operating cash flow of $64 million year to date, up from $50 million, adds credibility to the improvement.
The forward story centers on the affiliations. All 72 clinics are now converted: 62 with Metro/NYU Langone and 10 with Gulf Coast. That makes Q4 the first full quarter with both affiliations in place. Management said the affiliations are running ahead of the original $7.3 million 2027 EBITDA contribution target. It also pointed to more clinics joining existing agreements, de novos within the Metro footprint, and a pipeline of new hospital prospects. On reimbursement, the final 2027 CMS fee schedule sets a base PT rate increase of about 0.7%. It also phases out the IPCI modifier over two years starting in 2027, earlier than the 2028 timing flagged in Q2.
Bears still have legitimate points:
- **Commercial pricing:** commercial revenue per visit was flat after gains of 3.4% and 1.2% earlier in the year.
- **Health costs:** management cautioned that claims could pressure Q4 against a light 2025 comparison.
- **Debt:** credit facility borrowings climbed to $247 million from $162 million at year-end 2025. Quarterly interest expense rose to $3.6 million from $2.4 million. A new swap fixes term debt at 4.6% from mid-2027 through 2031.
- **Guidance:** with $75 million of adjusted EBITDA booked through September, the reaffirmed range implies Q4 EBITDA of roughly $27 million to $31 million. That is essentially a repeat of Q3, not a continuation of the acceleration.
Investor sentiment moved sharply the other way. It fell from -0.24 to -0.46, a substantial deterioration that deepened already-negative expectations. The stock tells a different story. Shares at $89.18 are up 18% since the open after the August report and sit about 16% above the 200-day moving average of $76.79. The Earnings Whispers trend signals are mostly positive, with sequential growth and price trends both favorable. That divergence suggests much of the operating improvement may already be reflected in the price, while skeptics remain focused on cost, leverage, and the unchanged outlook.
The bottom line is that USPH delivered a quality acceleration. Mature clinic growth, record rates, margin expansion through a cost headwind, and a hospital affiliation model gaining traction all point the same way. The conservative full-year guidance, rising health costs, flat commercial pricing, and heavier debt explain why investor sentiment soured even as the stock rallied. The next proof point is whether the first full quarter of both affiliations can push results above the ceiling management chose not to raise.
Read our earnings preview for U.S. Physical Therapy, Inc.: https://www.earningswhispers.com/article/USPH/21961
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Oct-27 | |
| Oct-21 | |
| Sep-21 | |
| Aug-27 | |
| Aug-14 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-22 | |
| Jul-02 | |
| May-14 | |
| May-06 |
