Cogent Faces A Credibility Test As Refinancing Costs And Revenue Slide Collide
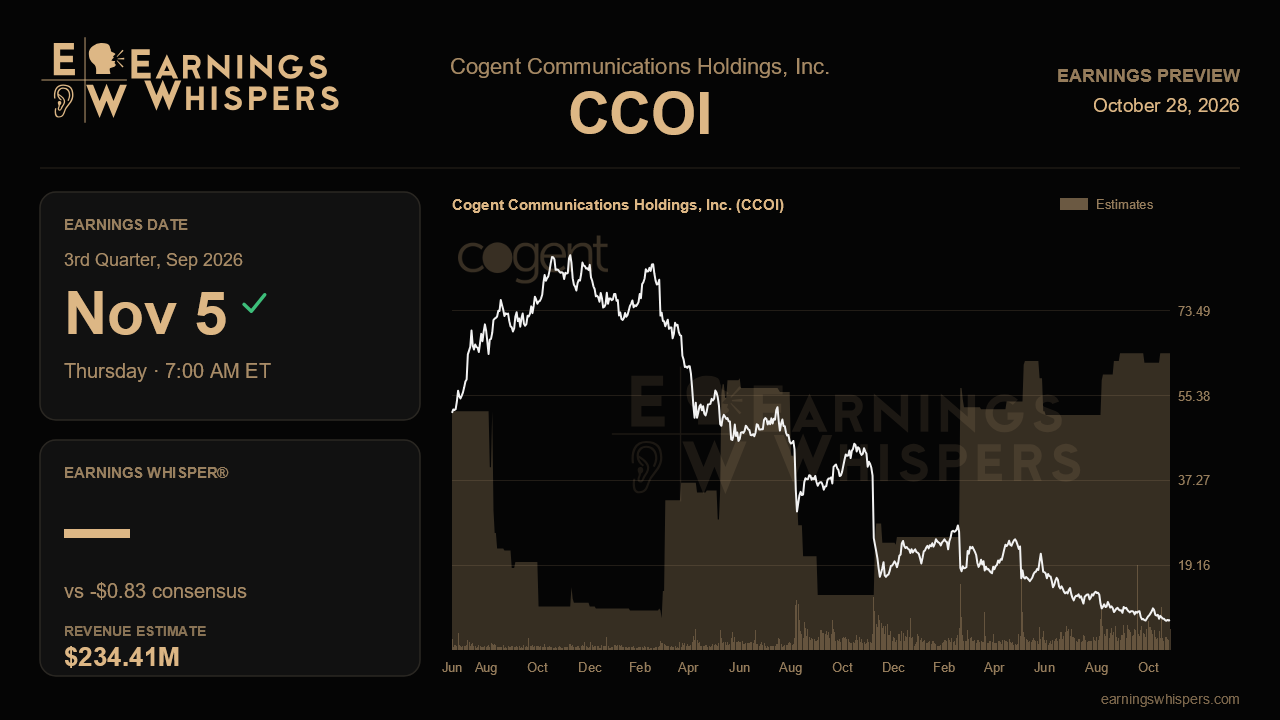
Cogent Communications heads into its September-quarter report with a stock that has lost nearly half its value since the last release and a narrative that has quietly split in two. The balance sheet is being repaired through asset sales and debt buybacks, but the operating business slipped back into decline just when management had promised growth. The November 5 report, due before the open, will show whether the cleanup can outrun the erosion.
The Street is not asking for much. Consensus calls for a loss of $0.83 per share, a modest improvement from the $0.87 loss a year ago but slightly worse than the $0.80 loss posted last quarter. Revenue is expected at $234.4 million, down 3.1% from a year earlier and roughly $1.2 million below the prior quarter. In other words, analysts are already modeling another sequential decline. That matters because management spent much of the past year saying revenue would return to sequential growth, a target first set for mid-2025 and reiterated on subsequent calls before revenue fell $3.6 million last quarter. With no formal guidance to anchor expectations, the top line itself has become the scorecard for management's credibility.
The most important operating question is whether wavelength services can finally convert strong demand into recognized revenue. Wave revenue grew about 60% year over year last quarter, and IP traffic accelerated to 16% growth, roughly double the market, helped by more symmetric traffic patterns tied to agentic AI. Yet wave installs came in light, customers remain constrained by power, data center space, GPUs and optics, and management stretched its 25% North American long-haul share goal from a mid-2028 framing to several years. The company also stopped disclosing its wave backlog, which removes a useful leading indicator. Evidence that installs picked up, alongside any early traction from the dedicated neocloud sales effort, would validate the demand story. Another quarter of strong orders but sluggish acceptance would reinforce the view that the opportunity keeps receding. IPv4 leasing, which decelerated sharply to just 0.5% sequential growth, is another line where stabilization would help.
On costs and cash, the company has more levers to show progress. Sprint synergies were lifted to $240 million and are largely captured, integration spending is falling below $3 million a month, and additional moderate headcount cuts were planned for this quarter. Last quarter EBITDA barely grew, weighed by severance, so cleaner expense lines should show whether operating leverage is real. The refinancing of the 2027 notes was expected to close this quarter on a secured basis, and the terms will be closely parsed given that existing secured paper yields near 9% versus 7% on the maturing unsecured debt. Higher interest costs make the free cash flow problem harder, and the CEO has already conceded the path to positive cash generation is challenging once T-Mobile subsidy payments end in under two years. Updates on the remaining roughly 55 megawatts of data center inventory, where four letters of intent were signed but deemed inadequate on price, could provide additional deleveraging firepower after net leverage improved to about 6.2 times.
Sentiment has collapsed alongside the share price. Bearish readings now run around 96%, compared with roughly 40% heading into the last report. At $7.47, the stock trades less than half its 200-day moving average of $16.04 and sits near the bottom of its post-earnings range of $7.04 to $13.49, a far cry from the prior quarter's $10.93 to $21.72 band. That washed-out positioning lowers the bar, though it does not guarantee relief.
Ultimately, the report hinges on whether Cogent can show a credible bridge from today's shrinking revenue and costlier debt to self-funding cash flow before the subsidies disappear. Stabilizing sales, faster wave acceptance and a refinancing that does not overly burden the income statement would keep the turnaround thesis alive. Another revenue slip paired with expensive debt would suggest balance-sheet progress is merely buying time.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-14 | |
| Sep-21 | |
| Sep-04 | |
| Sep-01 | |
| Sep-01 | |
| Aug-19 | |
| Aug-19 | |
| Aug-13 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-31 | |
| Jul-29 |
