Assured Guaranty Must Show Its Production Surge Can Survive Tougher Comparisons
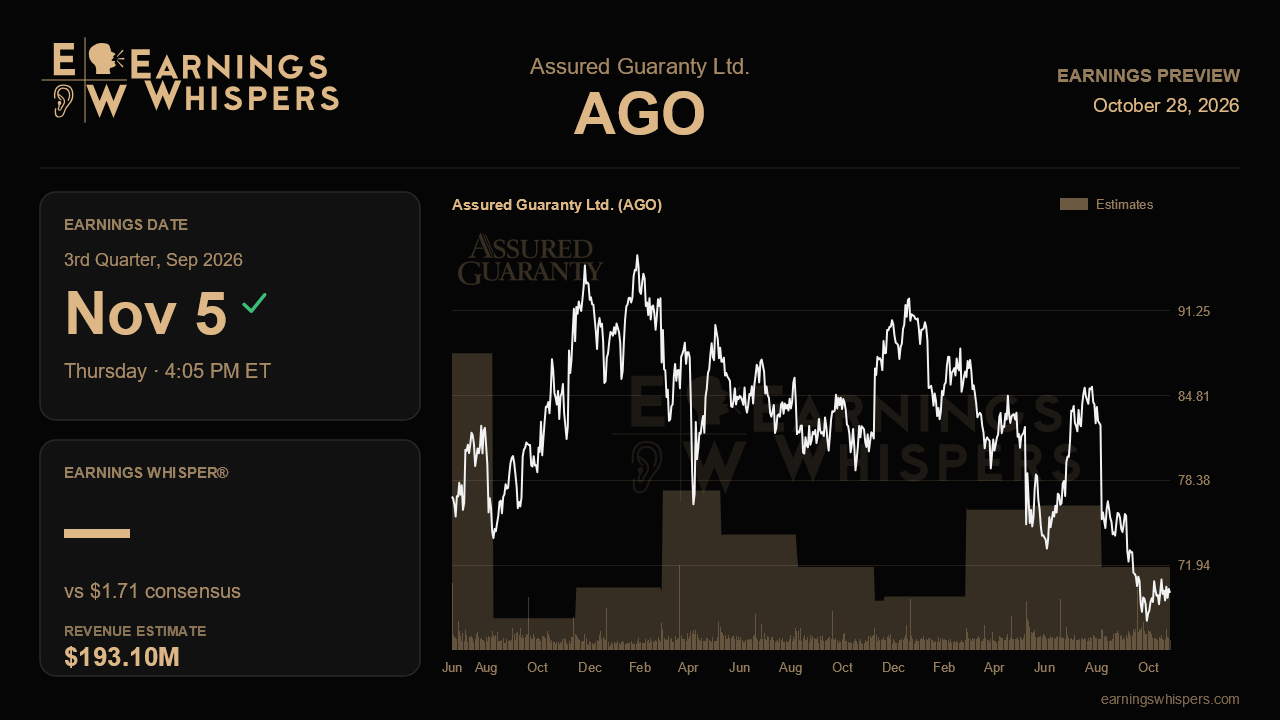
Assured Guaranty heads into its third-quarter report with a split personality. The insurer's underwriting engine is running hotter than it has in years, book value keeps setting records, and management sounded more confident on its last call than it has in some time. Yet the stock has dropped 12% since that report while the S&P 500 was essentially flat. The question for the November 5 release, due after the close, is whether the operating story can regain the market's attention, or whether the skeptics fixated on credit noise and slower buybacks have the better argument.
The headline numbers will look like a retreat. Consensus calls for EPS of $1.71, down 33.5% from $2.57 a year ago, on revenue of $193.1 million, a 6.7% decline. That is contraction on paper, but the more telling comparison is sequential. Last quarter Assured earned $1.23 per share on $195.0 million of revenue, so the Street is looking for roughly a 39% jump in per-share profit on flat revenue. With no formal guidance to anchor that estimate, the bar rests on things outside core premium growth. One is management's expectation that part of the $19 million mark-to-market loss on CLO equity, which weighed on alternative investments last quarter, would reverse. Another is keeping loss expense near the $4 million booked in the second quarter. If either fails to cooperate, the estimate looks ambitious.
New business is where the bullish case lives. First-half present value of new business premiums reached $152 million, up 48%, and U.S. public finance alone topped the entire company's first-half 2025 output. Structured finance more than doubled. Management said about $42 million of third-quarter production was already committed when it spoke, which serves as a floor rather than a target. The problem is the comparison: last year's third quarter produced $91 million, and executives openly flagged tougher second-half comps. A figure that clears the committed amount comfortably, helped by the new structured finance counterparties and the European toll road in the pipeline, would validate the momentum claim. A quarter that lands near $42 million would invite the conclusion that the first half was the peak.
The second test is Assured Life Re, the annuity reinsurance platform launched in January. Management said reception was strong enough to pull forward booking milestones. That matters because this business is now absorbing capital that once funded roughly $500 million a year of buybacks, cut to a target of about $30 million per quarter. Shareholders accepted that trade on the promise of growth, so concrete evidence of booked business, along with any progress on the soft or contingent capital facility floated earlier this year, will help justify the reallocation. Rising scheduled earned premiums from the fund finance flow business would add support.
Credit is the swing factor. The Brightline internal downgrade drove the largest economic loss development last quarter, albeit within deferred premium and without an operating income hit, and Thames Water remains unresolved. Further Brightline deterioration that begins to reach the income statement would challenge the clean-loss narrative.
Sentiment has softened from 26.5% bearish before the last report to 7.1% bearish now, so the crowd is less hostile even as the stock has slumped. Shares at $69.84 sit well below the 200-day moving average of $79.29 and only about 4% above the post-earnings low of $67.24, a range that has shifted noticeably lower than the prior quarter's. At roughly 37% of adjusted book value per share, the market is pricing in plenty of doubt. The report will turn on whether third-quarter production holds up against a demanding comparison while Brightline stays contained. Deliver both, and the case that capital is better spent on growth than buybacks gets much easier to make.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| Jul-21 | |
| May-09 | |
| May-07 | |
| May-07 |
