Assured Guaranty Beats As Production Accelerates And Brightline Settles, But Lower Buybacks Complicate The Discount-To-Book Story
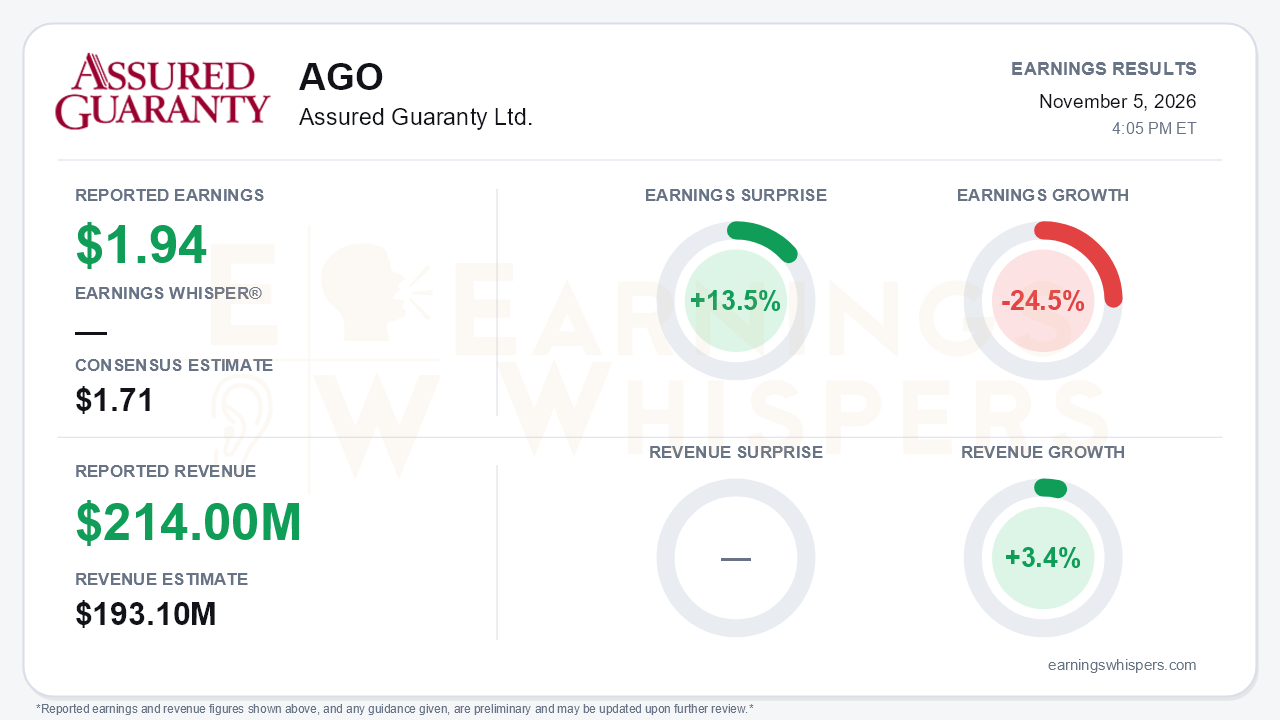
Assured Guaranty (NYSE: AGO) delivered a clean headline beat for the third quarter. Adjusted operating income was $1.94 per share, 13.5% above the $1.71 consensus, and revenue of $214.0 million topped the $193.1 million estimate by 10.8%. The year-over-year comparison is weaker. Earnings fell 24.5% while revenue grew only 3.4%. That gap is the central tension. The business is producing new premium at the fastest pace in years, but reported earnings are shrinking against an inflated prior-year base. Management is also returning noticeably less capital at a time when the stock trades well below book.
The quality of the beat deserves scrutiny in both directions. The year-over-year decline is mostly a comparison problem. Third-quarter 2025 included a $31 million loss benefit, $26 million of it from RMBS recoveries on charged-off second-lien loans. This quarter's loss expense was just $1 million. Investment income also softened:
- Trading securities swung from an $8 million gain to a $2 million loss.
- Equity in earnings of investees fell in both the Financial Guaranty segment and the Corporate division.
- The Corporate loss widened to $31 million from $24 million.
On the other side, part of the per-share result came from a shrinking share count, with diluted shares at 44.3 million versus 48.0 million a year earlier. Premium growth was also less organic than the headline suggests. Segment net earned premiums and credit derivative revenues rose to $115 million from $99 million, but accelerations and modifications contributed $18 million versus $6 million. Scheduled premiums grew a more modest $4 million to $97 million. On a GAAP basis, net income was $78 million, or $1.75 per share, down from $2.18. Rising rates pushed unrealized investment losses to $548 million, cutting GAAP equity per share to $122.91 from $125.32 at year-end.
The call preserved a credible growth story, and production is clearly the strongest part of it.
- **Nine-month production:** present value of new business production (PVP) reached $280 million, up 44%. That is nearly equal to the $286 million booked in all of 2025.
- **Breadth:** all three franchises contributed. U.S. public finance rose 31%, non-U.S. public finance rose 63%, and global structured finance more than doubled.
- **Third-quarter detail:** gross written premiums rose to $127 million from $75 million, and PVP climbed to $128 million from $91 million.
- **Deal flow:** activity included a $1.5 billion Hampton Roads military housing deal, a French toll road and the Anchorage port.
- **New guidance:** management gave its first explicit full-year PVP target of more than $400 million. The CEO said he would be "disappointed" at only $400 million.
- **Earnings mix:** short-duration fund finance now makes up roughly 27–30% of structured finance earned premium, versus about 5% two years ago. Management expects it to reach 30–40%, a shift that should speed up earnings recognition.
Brightline was the quarter's other key development. It moved from a first-half worry to a restructuring that brings $490 million of new capital, including a $70 million commitment from AGO. The credit was moved up a notch on the company's internal watch list, and it drove a $27 million net economic benefit. Adjusted operating equity per share reached a record $131.99 and adjusted book value per share a record $192.60, both up again from the second quarter.
Bears have legitimate ammunition on capital allocation:
- **Buybacks:** repurchases were just $10 million in the quarter, down from $45 million in the second quarter, $75 million in the first quarter and $500 million in 2025. Nothing was repurchased from October 1 through November 4, even with the stock below 60% of book.
- **Liquidity:** holding-company liquidity fell to roughly $144 million from about $179 million.
- **Capital needs:** Assured Life Re will consume capital, though it has not yet disclosed any new deals.
- **Alternatives:** the inception-to-date return on alternative investments slipped to about 11.5%, from 12% last quarter and 13% at year-end.
- **Pricing and credit:** tight credit spreads still limit pricing, and PREPA mediation has been extended to April 2027.
Management promised a fourth-quarter update on reinsurance-based "soft capital" initiatives that could free hard capital for buybacks. That makes the next report an important test.
The market setup is more complicated than the surprise implies. Investor sentiment improved substantially, moving from -0.27 before the prior report to a modestly positive 0.08. Sentiment has moved from skeptical to cautiously constructive, though it is not enthusiastic. The share price tells a less flattering story. At $71.76, the stock is down 9.5% from its opening price after the August report and sits about 8.9% below its 200-day moving average of $78.77. Record adjusted book value has so far failed to stop the stock's slide, and slower repurchases remove one of the clearest supports for a discounted stock.
The bottom line is that Assured Guaranty's underlying franchise looks healthier than its 24.5% earnings decline suggests. Production is accelerating, guidance points higher and Brightline has moved toward resolution. Even so, the beat leaned on accelerated premiums and a lower share count, and capital return has clearly taken a back seat to growth and new ventures. Investors are warming to the story. Whether the stock closes its discount to book likely depends on management showing that the soft-capital plan can restart meaningful buybacks while new business keeps building.
Read our earnings preview for Assured Guaranty Ltd.: https://www.earningswhispers.com/article/AGO/22228
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 |
