Ziff Davis Must Show Its Tech Recovery Can Outrun Health And Search Pressures
Ziff Davis heads into its third-quarter report as a different company than it was a year ago, and the question now is whether the leaner version can do more than shrink gracefully. The sale of the connectivity business to Accenture is done, the balance sheet holds a sizable net cash position, and the buyback has cut the share count sharply. What remains unproven is whether the four remaining segments can stabilize revenue, or whether per-share gains will keep leaning on financial engineering.
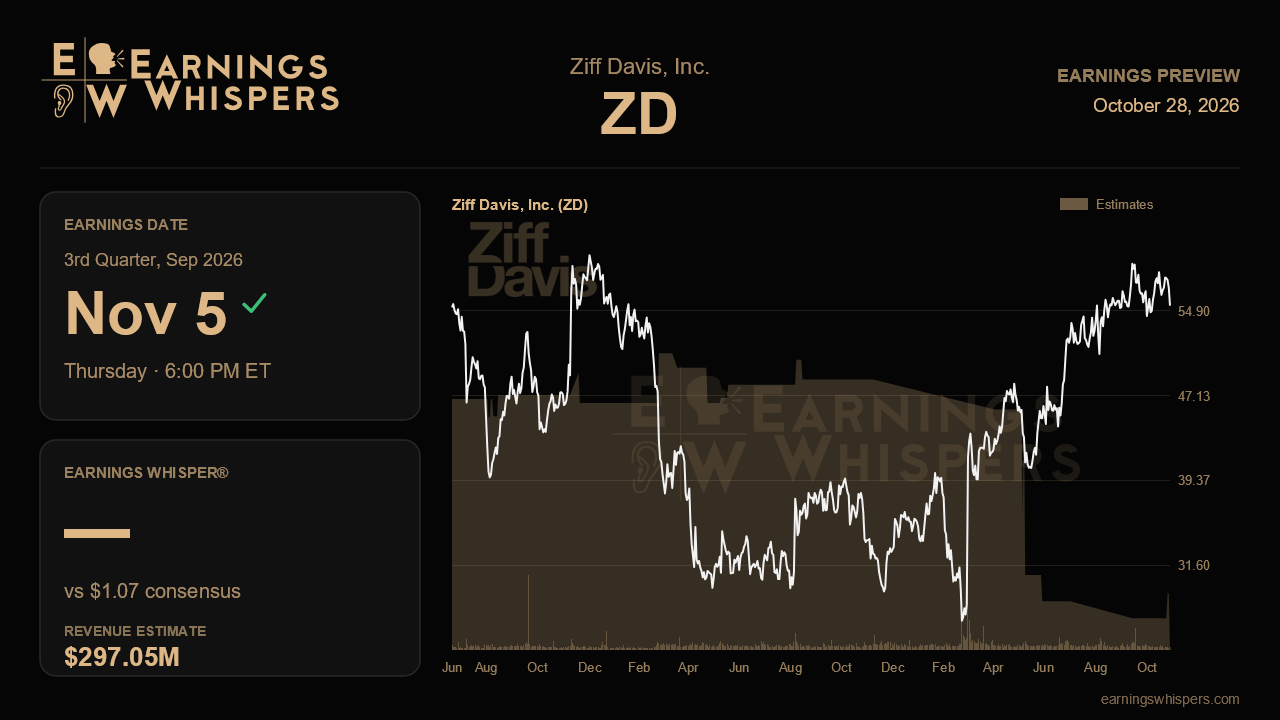
Wall Street expects earnings of $1.07 a share on revenue of $297.1 million. The headline revenue comparison looks ugly, an 18.3% decline from the $363.7 million reported a year ago, but most of that gap reflects the divested connectivity unit rather than a collapse in the core business. The more useful yardstick is sequential: consensus implies roughly 3.6% growth from last quarter's $286.7 million. That lines up with management's framing from the prior call, when it said the third quarter should look broadly similar to the second, with modest sequential revenue growth and slightly better margins, before the rate of decline narrows further in the fourth quarter. The Street, in other words, is sitting right on top of the company's own outlook rather than reaching beyond it.
The most important evidence will come from Tech & Shopping. Its revenue decline improved from 18% two quarters ago to 13% and then to just 5% last quarter, while segment profit rose. That trajectory underpins the second-half recovery thesis management has been building for several quarters. Another step toward flat would validate it; a stall or reversal would raise doubts, especially since AI Overviews now appear on about half of relevant search queries, up from roughly 36% a quarter earlier. Management has pointed to affiliate commissions generated through social channels as one offset to weaker search referrals, and this report should show whether that diversification is gaining traction.
Health & Wellness is the counterweight. Revenue fell 5% and segment profit dropped 10% last quarter as pharmaceutical advertisers moved MedPage spending toward cheaper AI-driven platforms. What management first described as a timing issue has started to look structural, so the key question is whether the bleeding has slowed. Newer initiatives such as GLP-1 support in Lose It, the hospital media network expansion that added UPMC, and new association job board partnerships need to start showing up as real offsets. Gaming is a smaller swing factor, with IGN advertising hurt by a thin release slate; commentary on the delayed GTA6 launch in November could frame fourth-quarter expectations. Margins also deserve attention, since management credited AI-authored code with letting it ship more software on a smaller engineering team and said nearly all code should be AI-written by year-end.
Sentiment has warmed noticeably, with readings only slightly bearish compared with a much gloomier mood heading into the last report. The stock tells a more cautious story. After a powerful run in the prior quarter, shares have slipped 2.8% since the last report while the S&P 500 was roughly flat. At $55.37, the stock sits in the lower half of its post-earnings range between $52.75 and $60.48, though still comfortably above its 200-day moving average near $47. That looks like consolidation after a big rerating, not a rejection of the story.
Cash flow is another area to examine. Management warned that second-half free cash flow conversion would be pressured by transaction fees and roughly $200 million in connectivity-related taxes, with a $149 million convertible note maturing this month. Updates on buyback pace and capital deployment after those obligations will matter. Ultimately, though, the report comes down to whether Tech & Shopping's improvement is durable enough to outweigh softness in Health. If it is, the turnaround narrative holds. If it is not, the buyback alone will have to carry the story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-15 | |
| Sep-21 | |
| Aug-19 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-29 | |
| Jul-16 | |
| Jun-04 | |
| May-19 |
