Ziff Davis Edges Past EPS Consensus, But Broadening Segment Declines And A Shelved Growth Target Undercut The Beat
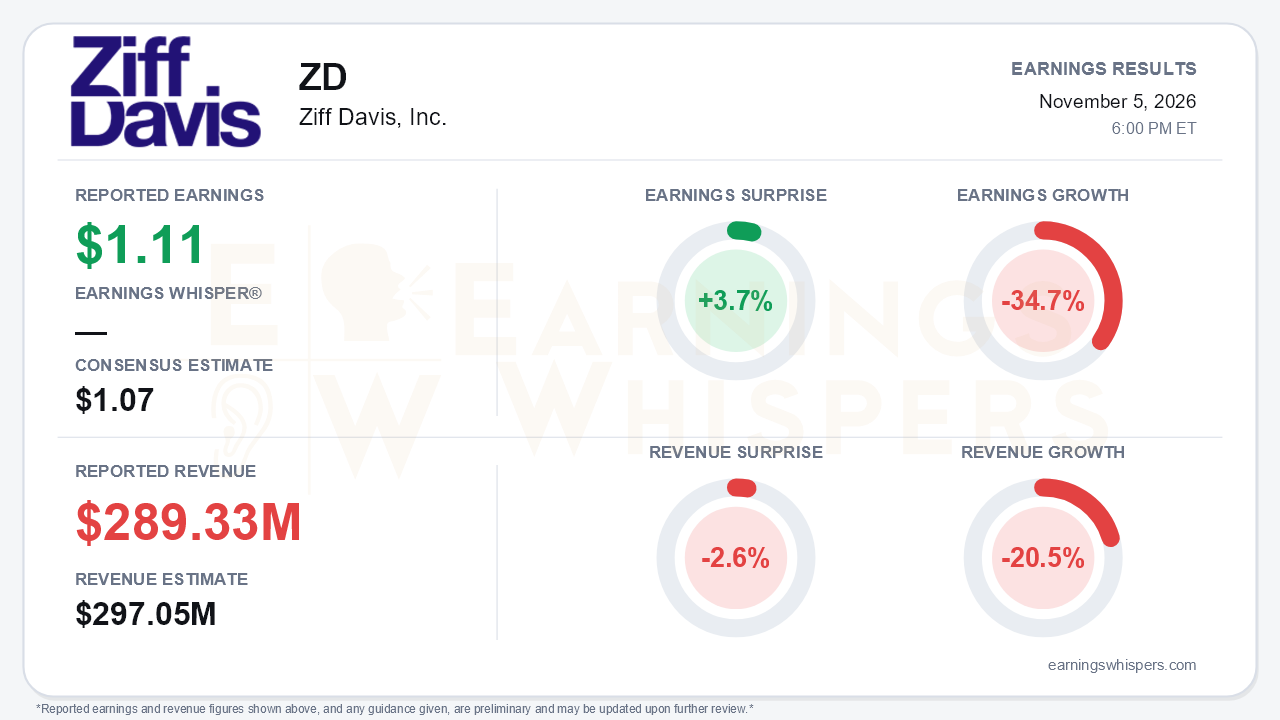
Ziff Davis cleared a modest earnings bar in the third quarter, but the quarter's real message is that the portfolio's weakness is spreading. Earnings Whispers puts EPS at $1.11, which beat the $1.07 consensus by 3.7% but fell 34.7% from a year ago. Revenue of $289.33 million missed the $297.05 million consensus by 2.6%. On the Earnings Whispers basis, revenue was down 20.5% year over year. That figure differs sharply from the company's own continuing-operations comparison, which shows a 5.6% decline from $306.5 million. The gap appears to reflect the comparison base following the second-quarter sale of the Connectivity business. Even the company's cleaner figure is the problem, though, because the continuing-operations decline has widened every quarter this year: -1.9% in Q1, -2.7% in Q2 and -5.6% in Q3. Management opened by saying results were 'in line with the expectations we set last quarter.' The fact that this is the selling point says a lot about where expectations have drifted.
The quality of the per-share result deserves scrutiny. The company's adjusted diluted EPS of $1.39 was essentially flat against $1.40 a year ago. That stability came from the denominator rather than the business. Adjusted net income fell 15% to $48.3 million, but buybacks cut weighted diluted shares from about 40.6 million to 33.8 million. Adjusted EBITDA dropped 16% to $82.2 million, and margin compressed 350 basis points to 28.4%. On a GAAP basis, the loss from continuing operations deepened to $0.85 per share from $0.39. The deeper loss reflects a $29.6 million goodwill impairment in Technology & Shopping and $14.5 million of long-lived asset impairments. Cash flow was distorted by the divestiture: free cash flow was -$100.1 million. Even after stripping out roughly $90 million of Connectivity-related taxes and fees, transaction-adjusted free cash flow was still negative at -$10.0 million, against +$108.2 million a year earlier.
The central tension is that the segment investors worried about most is healing while the segments that were supposed to carry the company have rolled over. Technology & Shopping's decline narrowed for a third straight quarter, from -18% in Q4 2025 to under -4% now, and management expects further improvement. The other three segments, all growing earlier this year, turned negative:
- Health & Wellness fell 9.5%, and management now calls MedPage's share loss in healthcare-professional advertising structural.
- Gaming & Entertainment slipped 2% on a weak gaming ad market.
- Cybersecurity & Martech fell 4.6% on softness in SEO tools and email marketing.
Underneath it all, organic Google referrals fell roughly 37% year over year, versus about 23% a year ago, and management described the decline as accelerating. The tone moved from 'transformative' last quarter to acknowledging that 'nothing's up in aggregate,' and the company is now planning for continued search erosion.
Guidance confirms the drift. On the first-quarter call, management targeted a return to year-over-year revenue growth in the second half. Q4 is now guided to a low-to-mid single-digit decline 'similar to, if not better than' Q3. The Q4 margin outlook has also slipped, from 'slightly down' to a decline into the low-to-mid 30s. The offsets are real but mostly forward-dated:
- An exclusive Harvard Health Publishing contract for the hospital media network.
- The loyalty-first RetailMeNot app relaunch, with September app commissions up 25%.
- GTA 6's November launch as a potential driver of 2027 gaming ad spend.
- About 2.7 billion AI Overview citations, positioned as leverage for content licensing.
Cost actions are doing visible work. Adjusted EBITDA margin rose 160 basis points sequentially, headcount is expected to fall about 10% by year-end, and Q4 adjusted EPS is guided slightly higher year over year. Bears still have legitimate ammunition on the balance sheet side. Roughly $145 million of the Connectivity tax bill remains due by Q1 2027, and net cash fell to $535 million from $734 million after buybacks and repayment of the $150 million convertible. Management has also halted most Lose It subscription marketing.
Investor sentiment was already negative and became modestly more so, moving from -0.19 to -0.23. The stock has drifted 4.7% lower since the open after the August report, to $54.28. It still sits about 14% above its 200-day moving average of $47.67. That positioning suggests the market has been giving credit for the buyback and the Tech & Shopping recovery more than it has been pricing in the deterioration elsewhere.
The bottom line is that Ziff Davis delivered a small EPS beat built largely on a shrinking share count, while revenue missed and the decline broadened across three of four segments. The improving Tech & Shopping trend and aggressive cost-cutting preserve a credible margin story. However, the abandoned second-half growth target, accelerating search losses and lingering tax outflows make the setup more fragile than the headline beat implies.
Read our earnings preview for Ziff Davis, Inc.: https://www.earningswhispers.com/article/ZD/22420
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-15 | |
| Sep-21 | |
| Aug-19 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 |
