Universal Faces Oversupply Test As Street Braces For Steep Earnings Drop
Universal Corporation heads into its fiscal second-quarter report with a stock that has already absorbed a lot of bad news and an earnings bar that has been pulled sharply lower. The leaf tobacco merchant is navigating a full oversupply cycle, with green prices falling and industry stocks building. Last quarter, management argued that the worst of the damage was cyclical and manageable. This report is the first real chance to check whether that argument holds once the busier shipping season gets underway.
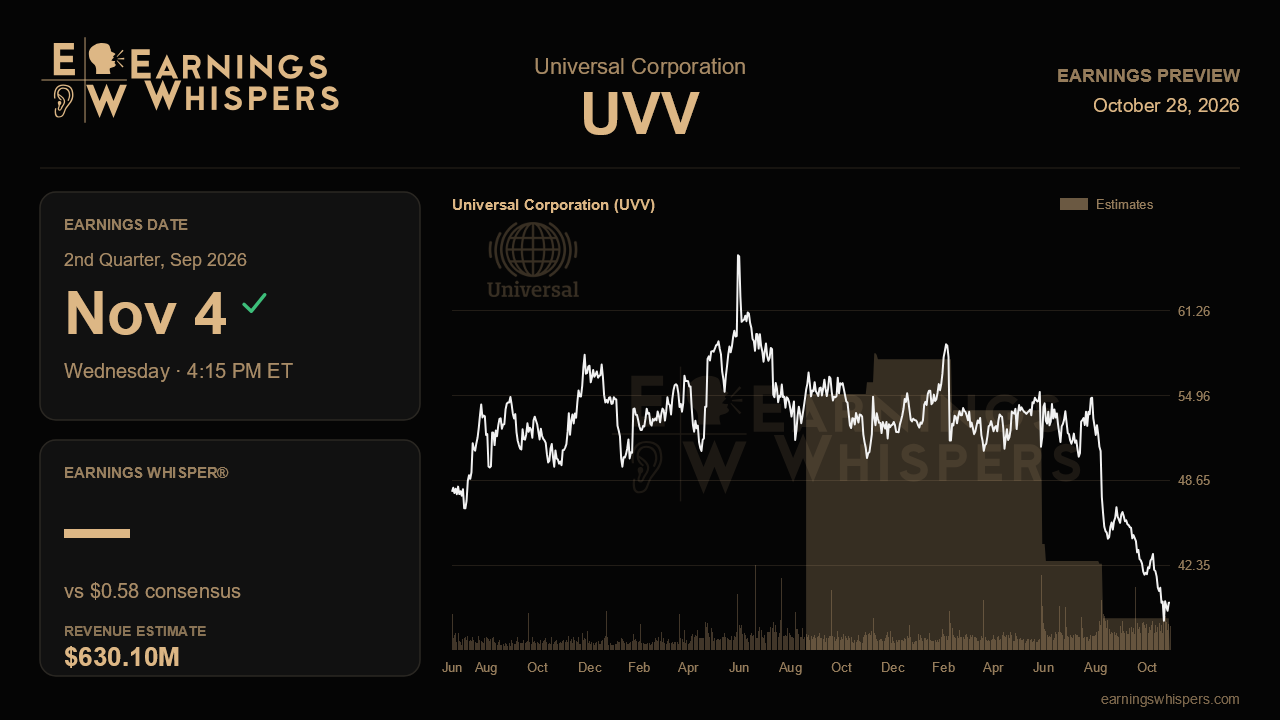
The Street is looking for earnings of $0.58 a share on revenue of about $630.1 million. That would be a 57.4% drop in profit and a 16.5% decline in sales from a year ago, when Universal earned $1.36 a share on $754.2 million in revenue. This is outright contraction, not a soft patch. A sequential rebound from last quarter's loss of $0.18 on $523.8 million in sales is expected, but that reflects normal seasonality. Management has not issued formal numeric guidance. The key reference point is its earlier reaffirmation of the fiscal 2027 sales plan, which it described as consistent with customer commitments.
The most important question is whether tobacco margins have bottomed. In the first quarter, segment profitability sank to a level that one analyst said she had never seen. Management blamed product mix and sales of carryover crop, and both should fade as current-crop shipments ramp. If second-quarter margins recover meaningfully, the case that the first quarter was a seasonal trough will look credible. If margins stay compressed even with higher volume, the market will likely conclude that lower green pricing is eroding the company's earning power more deeply, not just reshuffling the timing of shipments.
Inventory is the second test. Uncommitted flue-cured and burley stocks peaked near 27% at the end of March, against a target of roughly 20%. The CFO said levels had been falling since June and that he was comfortable reaching the target as the season progresses. Progress toward that number would support the CEO's other key assurance, that last year's $43 million in inventory write-downs should not recur. Any sign of renewed write-downs, especially in dark air-cured tobacco, would undercut the central pillar of the bull case. Lower working capital and lower interest expense, both promised last quarter, offer cleaner and quicker evidence that the balance sheet is easing.
Ingredients remains a nagging drag. Lancaster utilization was described as relatively low, the segment is searching for a new leader, and management framed the recovery as incremental and slow. Nobody expects a turnaround this quarter. Still, signs that losses are narrowing, or that capital spending is being redirected toward tobacco automation as planned, would help. Possible upside surprises include customers buying extra volume to hedge El Niño crop risk and tariff refunds starting to flow, though neither has been quantified.
The market has been unforgiving. Shares have fallen 24.7% since the last report, about 25 points worse than the S&P 500. At $39.55, the stock sits well below its 200-day moving average of $50.51 and near the bottom of its post-earnings range of $38.11 to $53.82. Sentiment has edged up to 6.9% bullish from 3.3%, which is still only lukewarm. A heavily discounted stock can respond well to simple reassurance, but it can also break support if the cyclical story starts to look structural.
In the end, the report turns on one issue. Universal needs to show that recovering tobacco margins, a shrinking uncommitted inventory position and the absence of write-downs can coexist with falling leaf prices. If it can, the reaffirmed annual plan stays intact. If it cannot, the oversupply cycle may prove longer and costlier than management has suggested.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Oct-10 | |
| Aug-30 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-27 | |
| Jul-16 | |
| Jul-16 | |
| Jun-07 | |
| May-29 |
