EPlus Must Start Turning A Record $1.5 Billion Backlog Into Revenue
ePlus enters its fiscal second-quarter report with a clear gap between what customers have ordered and what the company has delivered. Last quarter, orders kept piling up: total backlog topped $1.5 billion and open orders rose more than $650 million from a year earlier. Reported results told a different story. Net sales grew just 1%, gross margin slipped, and adjusted EBITDA fell about 9%. Management blamed timing, citing a tough enterprise comparison and delivery delays tied to the global memory shortage. This report is the first real test of whether that explanation holds.
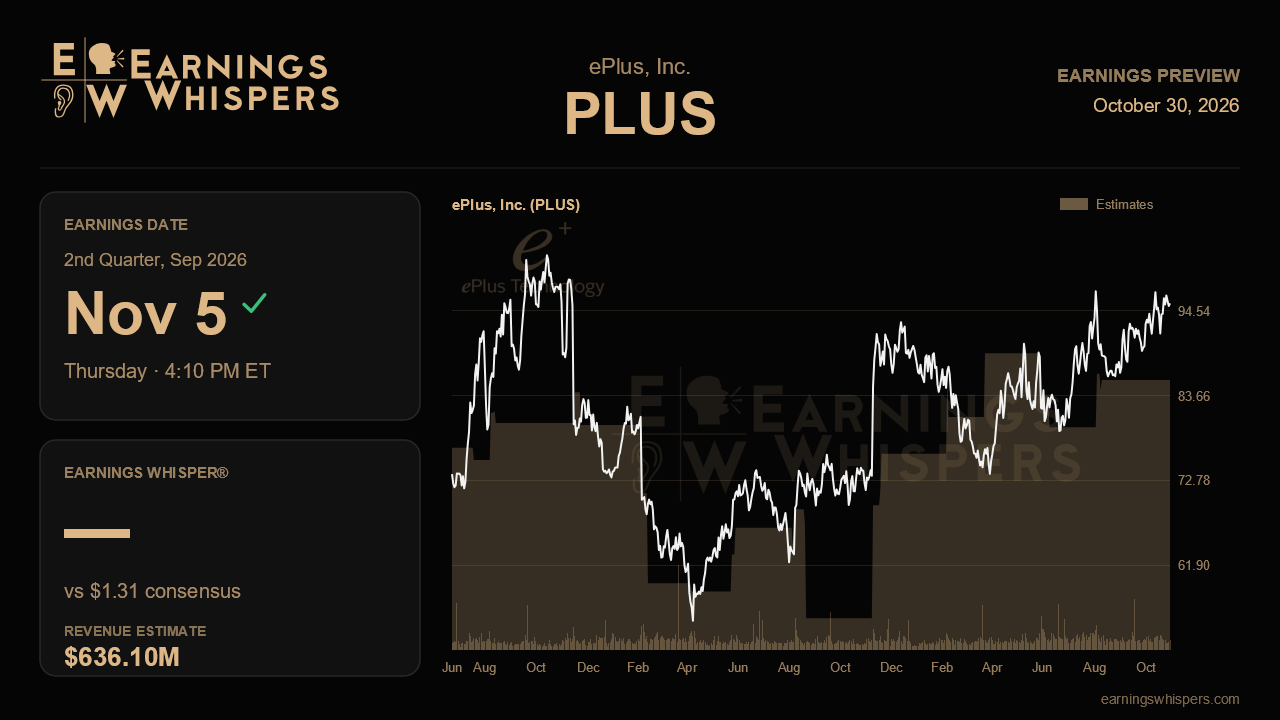
The Street is not asking for much. Consensus calls for EPS of $1.31, about 10% below the $1.45 earned a year ago, on revenue of roughly $636.1 million, up a modest 4.5%. That revenue figure sits below the $649.1 million reported last quarter, so analysts are effectively modeling a small sequential decline even with a record backlog. The EPS estimate is only slightly above last quarter's non-GAAP $1.28, which suggests the market expects continued margin pressure rather than a quick recovery. Management kept its full-year outlook of mid-single-digit growth in sales, gross profit and EBITDA. Unlike the raises in fiscal 2026, though, it did not lift the targets. A quarter near consensus keeps that guidance plausible, but the second half would then have to carry more of the load.
The main question is conversion. Management said most of the backlog is not ratable and will take time to work through. That leaves room for patience, but also for disappointment if delivery timing slips again. Revenue clearly above $636 million, along with a steady or shrinking backlog, would suggest product is finally shipping. A backlog that keeps rising while sales stall would support the demand story but deepen worries about execution and memory supply. Professional services matters here too. That business fell 5.1% last quarter because of delayed product deliveries and a retail project management could not say when would resume. Stabilization there would be early evidence that hardware is flowing again.
Margins are the second swing factor. Gross margin has fallen four straight quarters, from 26.6% to 23.3%, and every segment weakened last time. Management also pointed to spending on customer-facing hires and professional fees. Some of that pressure is reasonable while a company invests ahead of AI infrastructure demand. Another drop in gross margin, though, would raise doubts about pricing power in a product mix tilting toward large data-center deals. The faster-growing parts of the business offer some support. Managed services topped $50 million and has accelerated for several quarters, and security billings rose more than 15%. Continued strength in these steadier lines would help offset choppy hardware timing.
The mood going in has improved. Sentiment has moved from clearly bearish before the last report to roughly neutral now. The stock, however, has slightly lagged a weak S&P 500 since the last print. Shares trade near $95, well above the 200-day moving average around $86 and within 3% of the post-earnings high of $98.21. That level also matches the prior quarter's peak, creating a clear ceiling the stock is now testing. A strong report could push it through. A weak one would leave a stock priced for recovery with little cushion.
In the end, the quarter comes down to whether the record backlog starts to show up as revenue and stable margins. If deliveries pick up and gross margin holds, management's timing explanation and its unchanged full-year guidance both look credible. If orders keep outrunning shipments, the market may begin to doubt both.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-20 | |
| Sep-02 | |
| Aug-24 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-21 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 | |
| Jun-25 | |
| Jun-23 | |
| Jun-22 |
