EPlus Beats And Raises On Cloud-Led Reacceleration, But Services Slippage And A Cash-Draining Inventory Build Leave Execution Questions
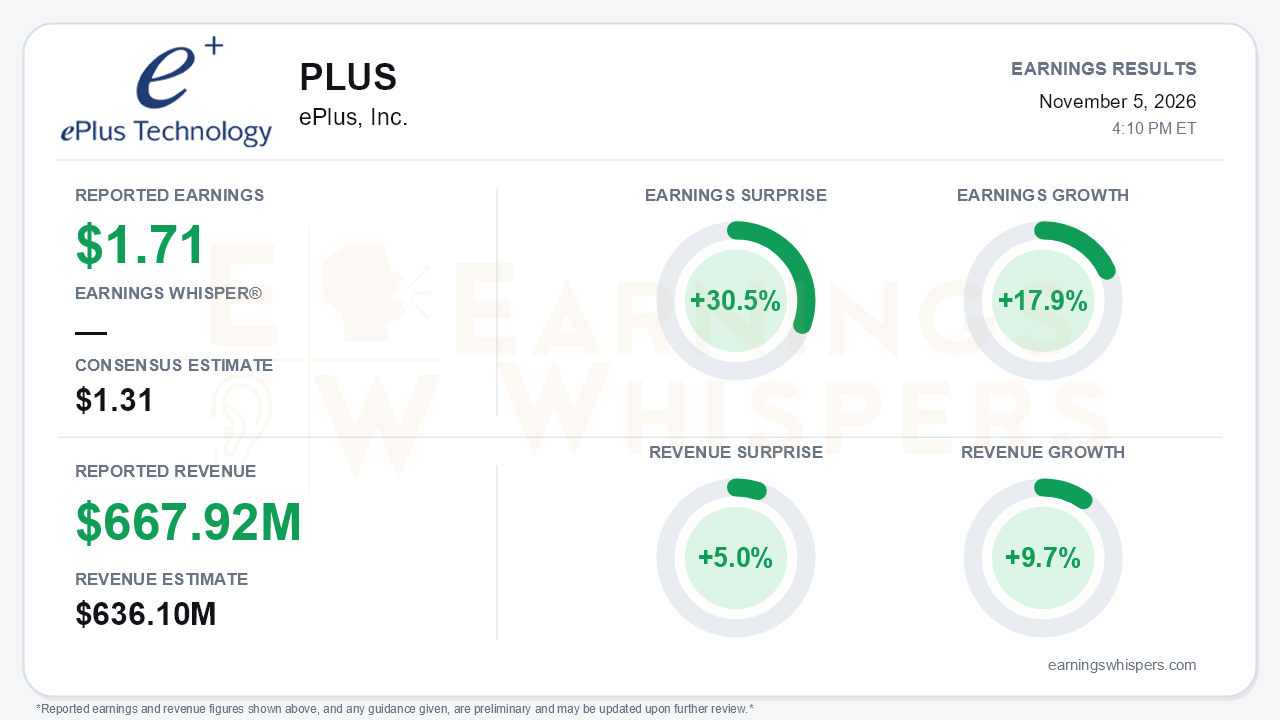
ePlus delivered the reacceleration that a flat first quarter had called into question. The company reported fiscal second-quarter earnings of $1.71 per share, 30.5% above the $1.31 consensus, and up 17.9% from a year earlier. Revenue rose 9.7% to $667.9 million, 5.0% ahead of the $636.1 million consensus. That compares with net sales growth of just 1.0% and a 9% decline in adjusted EBITDA in the first quarter. Management then raised full-year guidance across every metric it provides. The central tension is that the product and cloud engine is clearly firing while the services business keeps eroding, and a large working-capital build is consuming cash ahead of second-half deliveries.
The quality of the beat is good at the operating line and noisier below it. Product sales rose 12.8% to $547.1 million. Product gross margin climbed to 25.8% from 24.5% a year ago and from 21.0% in the first quarter, helped by mix and more net-recognized maintenance and subscription sales. Cloud net sales jumped 39.2%, offsetting a 9.2% drop in networking. Consolidated gross margin reached 27.0%, operating income rose 15.8%, and adjusted EBITDA increased 14.3% to $67.1 million. Investors should note the per-share bases differ. GAAP continuing EPS was $1.56, up 7.6%, while the company's own non-GAAP figure was $1.82, up 19.0%. The gap reflects other income swinging to a $0.5 million loss from a $5.2 million gain, including a $3.5 million write-down of contingent consideration tied to the sale of the financing business. That swing held GAAP pre-tax growth to 3.7%. A lower tax rate and fewer diluted shares helped bridge the rest. The release also notes immaterial revisions to correct prior misstatements, which is worth tracking in the 10-Q.
The call made the demand case more concrete. Open orders topped $1.8 billion, up roughly $750 million from a year earlier and about $300 million sequentially, led by data center, cloud and AI. Gross billings set a record above $1.06 billion, although their 4.3% growth was more modest than net sales growth. Financial services sales surged 48.3% and healthcare rose 22.0%, offsetting a 12.9% decline in telecom, media and entertainment. Management described AI adoption as accelerating and cited multimillion-dollar wins with a neocloud, a service provider, a utility and defense-tech customers. It also added credentials through the Daymark acquisition, which brings Northeast reach and Microsoft Tier 1 CSP status, and through certification in Anthropic's Claude Partner Network. The guidance raise lifts net sales and gross profit growth to upper single digits and adjusted EBITDA to low double digits, from mid-single digits for all three. That spread signals management expects operating leverage.
Bears still have legitimate ammunition. Professional services revenue fell 11.3%, and segment margin slid to 35.4% from 38.2% on retail-customer project delays. This extends a pattern flagged in each of the prior two quarters. Overall services margin dropped to 32.5% from 34.8%, and managed services margin slipped despite 11.9% revenue growth. Cash fell to $380.9 million from $448.9 million at the end of the first quarter. Inventory rose 35.1% since March to $271.4 million, and receivables climbed 14.9%. The release attributes the inventory to several ongoing projects, while the call tied the build largely to one large customer, which raises concentration and execution risk. Because first-half adjusted EBITDA grew only 3.2%, the raised outlook requires a much stronger second half. Yet management acknowledged that part of the backlog will slip into fiscal 2028 and that GPU, memory and networking supply constraints and price increases persist.
Investors were not positioned for this degree of improvement. Earnings Whispers sentiment remained negative but improved meaningfully, moving from -0.19 to -0.10. Shares entered the report at $90.47, down 6.9% from the $97.20 open after the prior release. The stock sat 7.9% below the 52-week high of $98.21 set on October 26 and 6.5% above its late-August low, near the middle of its inter-earnings range. Price and AVWAP trend readings were positive, while the sequential-growth reading remained negative, a reminder of how soft the first quarter was.
The bottom line is that ePlus turned a stalled first half into a credible growth story, backed by a record backlog, expanding product margins and a guidance raise that implies operating leverage. The open questions are whether the company can convert a concentrated inventory build into second-half revenue on schedule, and whether professional services can stop bleeding. Those answers will determine whether this quarter marks a durable inflection or a well-timed product surge.
Read our earnings preview for ePlus, Inc.: https://www.earningswhispers.com/article/PLUS/22536
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-29 | |
| Oct-20 | |
| Sep-02 | |
| Aug-24 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-21 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 |
