EPlus Beats Big And Raises Guidance As AI-Driven Product Surge And $1.8 Billion Backlog Outweigh Services Softness
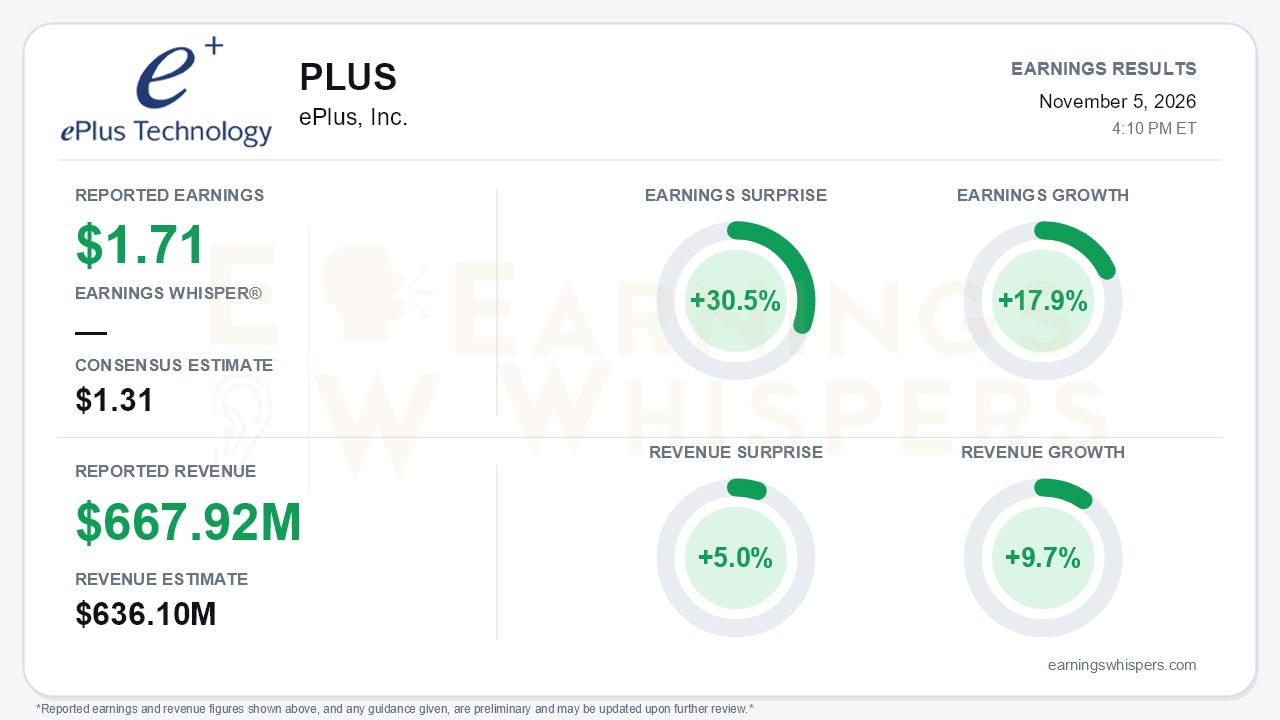
ePlus delivered a decisive beat for its fiscal second quarter, and the more important development is the reacceleration behind it. Earnings of $1.71 per share topped the $1.31 consensus by 30.5% and grew 17.9% year over year. Revenue of $667.9 million beat the $636.1 million estimate by 5.0% and rose 9.7%, a sharp step up from roughly 1% growth in the first quarter. Management converted that momentum into its first guidance increase of the fiscal year. Net sales and gross profit growth are now expected in the upper single digits, up from mid-single digits, and adjusted EBITDA growth in the low double digits. Note the per-share comparisons: the company reported GAAP continuing-operations EPS of $1.56 and non-GAAP EPS of $1.82, up 19.0%, so the normalized $1.71 sits between the two company-defined measures.
The quality of the beat holds up better than most, but it is concentrated. Product sales rose 12.8% to $547.1 million, and cloud product sales jumped 39.2%, which management tied to AI-related data center demand along with NeoCloud and DefenseTech wins. Networking, still the largest billings category, fell 9.2%. Margins did the heavy lifting:
- Consolidated gross margin reached 27.0%, up from 26.6% a year ago and a striking jump from 23.3% in the first quarter.
- Product margin climbed to 25.8% from 24.5%, helped by mix and by more net-basis maintenance and subscription sales. That flatters percentage margins as much as it reflects pricing power.
- Operating income rose 15.8% and adjusted EBITDA 14.3%.
Below the line, a $3.5 million markdown of contingent consideration from the financing-business sale, plus lower interest income, held pretax earnings growth to just 3.7%. That gap explains why GAAP EPS growth lagged the operating story.
The call reinforced the case that demand is building rather than peaking. Open orders exceeded $1.8 billion, up about $750 million year over year and roughly $300 million sequentially, versus a $650 million year-over-year increase last quarter. Gross billings hit a record $1.07 billion. End-market data shows real breadth: financial services sales rose 48.3% and healthcare 22.0%, offsetting a 12.9% decline in telecom, media and entertainment. Strategic additions round out the picture:
- the Daymark Solutions acquisition, bringing Northeast reach and Microsoft Tier 1 CSP certification;
- certified services-partner status in Anthropic's Cloud Partner Network;
- exclusive ambassador status with Everpure.
Bears still have legitimate ammunition.
- **Professional services:** revenue fell 11.3%, and segment margin slid to 35.4% from 38.2%. Retail project delays have now been cited for a fourth straight call, and the earlier expectation of normalization this fiscal year has not materialized.
- **Services margin:** overall services gross margin dropped to 32.5% from 34.8% on higher third-party costs.
- **Working capital:** inventory rose to $271.4 million, up 35.1% since March, tied largely to one large customer's projects slated to ship in the second half. Receivables rose 14.9%. Cash fell to $380.9 million, down from $448.9 million at the end of the prior quarter and $410.8 million at fiscal year-end.
- **Supply and timing:** memory and GPU constraints continue to delay high-end compute and networking. Management acknowledged that a large portion of open orders will slip into fiscal 2028.
The raised outlook therefore leans on a back half that must deliver. First-half adjusted EBITDA grew only 3.2%, so low-double-digit full-year growth implies meaningful acceleration and successful conversion of that concentrated inventory.
The market setup is more constructive than the price change since August suggests. Shares closed at $90.47 before the report, down 6.9% from the $97.20 open after the prior release. However, they sat 5.4% above the 200-day moving average and roughly mid-range between the August low of $84.93 and the 52-week high of $98.21 set October 26. Investor sentiment improved from -0.19 to -0.10, a moderate move that leaves expectations still slightly negative. That gives a beat-and-raise of this size room to reset the narrative. Most Earnings Whispers trend readings lean positive, though the sequential-growth reading remains negative, consistent with a first half that was weaker than this quarter.
The bottom line is that ePlus turned a sluggish first quarter into a genuine beat-and-raise, built on AI-driven cloud demand, a swelling backlog and notably stronger product margins. The headline is credible, but it rests on product strength while professional services keeps eroding, and on a cash-consuming inventory build tied to a single large customer. Second-half conversion of that backlog will determine whether this quarter marks a durable inflection or a well-timed spike.
Read our earnings preview for ePlus, Inc.: https://www.earningswhispers.com/article/PLUS/22536
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-29 | |
| Oct-20 | |
| Sep-02 | |
| Aug-24 | |
| Aug-05 | |
| Aug-04 | |
| Jul-28 | |
| Jul-21 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 |
