Life360 Must Prove Subscription Momentum Can Outrun Advertising Doubts As Shares Slide
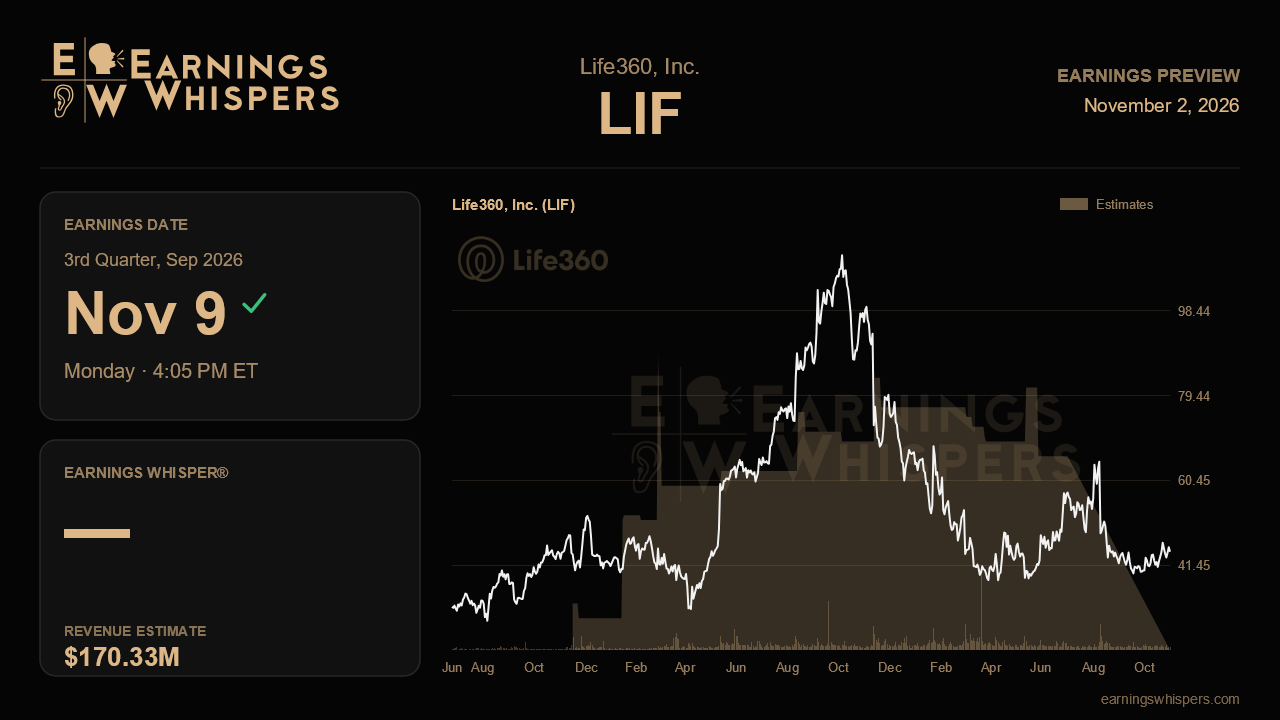
Life360 heads into its third-quarter report with an odd disconnect. Last quarter, management described a subscription engine that had shaken off its first-quarter stumble: monthly active users crossed 100 million, net subscriber additions set a second-quarter record, and subscription revenue guidance rose for the second straight time. Yet the company left full-year revenue and profit guidance unchanged, and the stock has since fallen 11.1%, trailing the S&P 500 by nearly nine percentage points. The November 9 report, due after the close, needs to show which of those two stories deserves more weight.
Wall Street expects revenue of about $170.3 million, up 36.8% from $124.5 million a year ago and roughly 7% above the $159.0 million posted in the second quarter. That growth rate is essentially in line with the 38% pace of the first half, so the bar assumes no slowdown rather than an acceleration. Management has reaffirmed full-year revenue of $650 million to $685 million, and the consensus of about $669.7 million sits slightly above the midpoint. Combined with first-half results, the Street's third-quarter figure implies a fourth quarter near $197 million. That back-loaded target matters because management named fourth-quarter advertising seasonality as the main reason it declined to raise the overall outlook.
The cleanest test is whether the user and subscriber recovery holds up. Management had promised that MAU growth would return to its planned trajectory by the third quarter, and the second quarter's 4.6 million additions suggested that work was finished early. Another solid quarter of user gains, especially internationally where growth ran at 20%, would support the view that the earlier technical problems are behind the company. The back-to-school season adds a specific checkpoint, with the new AT&T partnership in Mexico and rising brand awareness in Brazil and Mexico offering early evidence on whether Latin America is nearing the penetration level management views as an inflection point. On monetization, the $2 monthly price increase for new U.S. subscribers and the PetGPS bundle relaunch should begin to show up in average revenue per paying circle, which dipped slightly last quarter. A rebound there would validate pricing power; a further slip would raise questions.
The profit picture is messier. Management signaled that marketing spending would shift into the third quarter, so adjusted EBITDA margin is unlikely to match the 20% reached in the second quarter, and a dip should not be read as deterioration on its own. More telling will be advertising gross margin, which slid to 57% as the company built out a lower-margin managed-service business, and hardware, where guidance was cut and an underlying margin near 7% was masked by a one-time tariff refund. Advertising revenue of roughly $22 million last quarter needs to keep growing if the integrated Nativo platform and its near-total coverage of the U.S. addressable ad market are to justify the expense.
Investor mood has soured. Sentiment readings are more bearish than they were ahead of the last report, and the stock, at $44.44, trades below its 200-day moving average of $47.17 and in the lower half of its post-earnings range of $39.31 to $53.45. That range is far narrower than the previous quarter's swing from $37.65 to $65.57, suggesting the extreme volatility has cooled even as conviction has faded. With $212 million left on its buyback authorization, the pace of repurchases at these lower prices will also say something about management's own confidence.
Ultimately, the report hinges on whether subscription strength is durable enough to carry the consolidated outlook through a risky advertising-heavy fourth quarter. If Life360 delivers steady user and subscriber growth, firmer pricing metrics and reassurance on ad seasonality, the recent selloff will look like an overreaction. If it trims the revenue range or leans on subscription gains to offset weakening advertising and hardware, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-27 | |
| Aug-27 | |
| Aug-25 | |
| Aug-10 |
Life360 Stock Plunges On Mixed Second-Quarter Report, Soft Full-Year Outlook
LIF LIF -24.76%
Investor's Business Daily
|
| Aug-10 | |
| Jun-18 | |
| May-19 | |
| May-17 | |
| May-12 | |
| May-11 | |
| Mar-19 | |
| Mar-06 | |
| Mar-04 | |
| Mar-02 |
