Life360 Accelerates To 40% Growth As Subscription Engine Carries The Quarter And Advertising Resets Lower
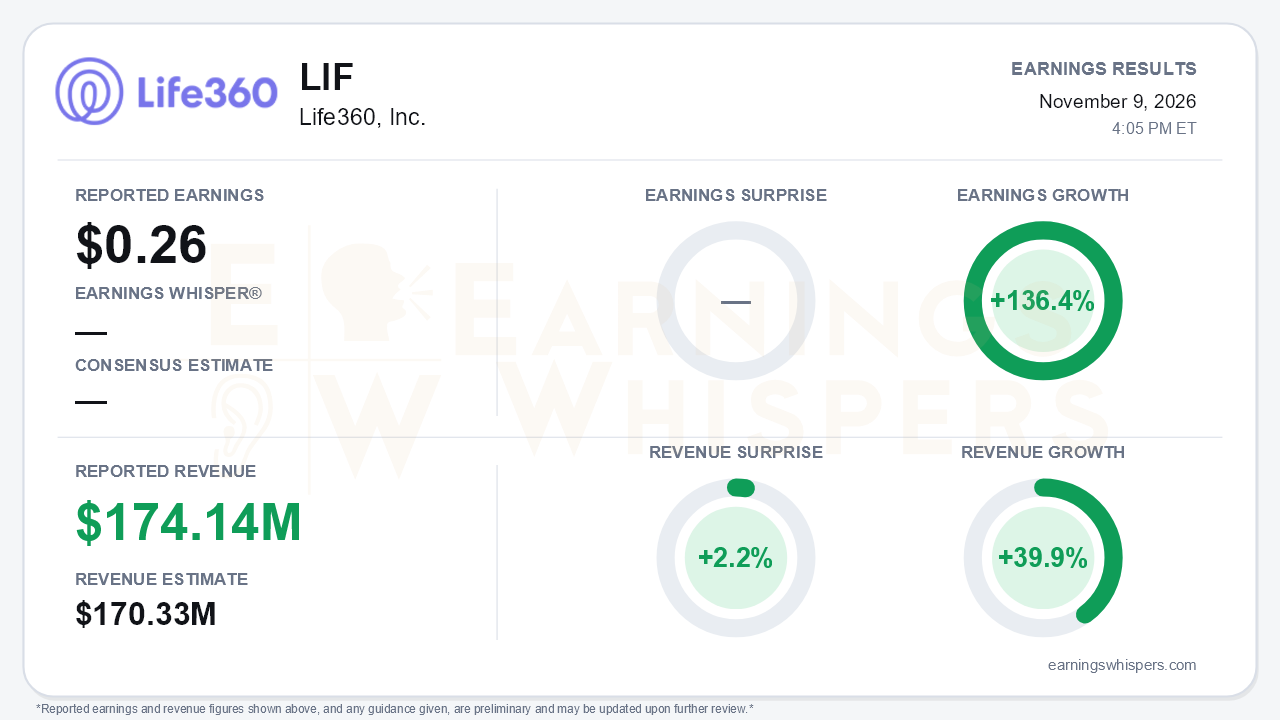
Life360 delivered the revenue acceleration management promised, but beneath the headline the quarter split into two businesses moving in opposite directions. Revenue of $174.14 million rose 39.9% year over year and beat the $170.33 million consensus by 2.2%. That was an improvement from 38% growth in both the first and second quarters. GAAP earnings of $0.26 per diluted share grew 136.4% from the prior-year period. The subscription franchise is getting stronger. Advertising, the newer growth leg built around the Nativo acquisition, undershot and had its outlook trimmed. That is the central tension. Life360 raised total revenue guidance, yet adjusted EBITDA guidance was only narrowed to $132 million to $138 million. Its midpoint remains $135 million, where it has been since the first quarter.
The quality of the EPS figure deserves scrutiny. Net income of $22.5 million included a $17.5 million net gain on the fair value of investments. The call attributed a $17.8 million gain specifically to the Hubble investment, a slightly different figure than the release's net number. GAAP operating income was only $8.0 million, and for the first nine months the company posted a small operating loss. The cleaner operating read is adjusted EBITDA, a non-GAAP measure. It rose 41% to $34.6 million at a 20% margin, ahead of the 18% management had guided. Part of that upside came from early, high-margin partnership revenue, including a $3.7 million catch-up payment within other revenue. Operating expenses fell to 72% of revenue from 80% in the second quarter, so operating leverage is real. Even so, operating cash flow grew just 3% to $27.2 million.
The subscription story is the strongest part of the report. Paying Circles grew 26% to 3.4 million on a third-quarter record of 188,000 net additions. Core subscription revenue rose 32%, and subscription gross margin improved to 87%. Annualized Monthly Revenue climbed to $578.0 million from $537.2 million in the second quarter. Monthly active users added 5.3 million to reach 107.7 million, and international MAU passed 50 million. Subscription guidance has now been raised for a third straight quarter, to $483 million to $488 million. Pricing is the next lever. The U.S. price increase is being extended to the existing base, with Gold rising about $2 a month, or roughly 13%, and full impact expected in 2027. Management also said an AI-driven funnel doubled the share of new subscribers choosing Platinum, now about 5% of the mix.
Advertising is where bears have legitimate ammunition. Ad revenue of $25.4 million increased from $22 million in the second quarter, but it landed at the low end of expectations. Organic ad growth was described as only in the low 20s. The full-year ad guide fell to $98 million to $102 million from $98 million to $115 million. Management cited sales-motion and ad-quality adjustments, a pause in programmatic ads, and missed 2026 budgets. Ad gross margin slid to 55% from 57% in the second quarter and 60% in the first. That leaves it well short of the 65% to 70% fourth-quarter normalization target set last quarter, and it pulled total gross margin down to 77%. Hardware is a smaller drag: revenue fell 20%, gross margin was negative 19% as Pet GPS ramps, and guidance was cut again. The hiring of Donna Sharp to lead Life360 Ads and the positive brand signals management cited for 2027 are the counterweights, but both are promises rather than results.
The forward setup carries some deliberate near-term softness. Management expects U.S. Paying Circle net additions in the fourth quarter to run at roughly half of normal levels because of churn from the price increase. MAU growth is tracking the low end of the 17% to 20% range, down from the 20% target set at the start of the year. Acquisition marketing in Mexico and Brazil is being pulled back while the product is localized. Against that, buybacks reached $44.4 million, more than offsetting stock-based compensation dilution. The family-intelligence platform has also been opened to third-party AI agents such as Meta's Muse.
The market had already turned skeptical between reports. Shares opened at $50.00 after the August release and peaked at $53.45 that day. They then slid to an inter-earnings low of $39.31 on October 1, well below the 200-day moving average near $46.86. Investor sentiment entering the report was modestly negative at roughly -0.21. That suggests expectations had been reset lower after the post-August fade. The Earnings Whispers sequential growth, momentum, and AVWAP trend readings are positive, while the price trend is neutral.
The bottom line is that Life360's core subscription business strengthened again, with record third-quarter Paying Circle additions, rising ARPPC, and a third consecutive subscription guidance raise. The advertising expansion, however, is proving slower and less profitable than planned. The headline EPS growth leans heavily on an investment gain, and the unchanged EBITDA midpoint shows that the ad and hardware shortfalls are absorbing the subscription upside. Investors are effectively being asked to trust pricing-driven subscription growth while waiting for advertising to prove its 2027 case.
Read our earnings preview for Life360, Inc.: https://www.earningswhispers.com/article/LIF/22646
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-27 | |
| Aug-27 | |
| Aug-25 | |
| Aug-10 |
Life360 Stock Plunges On Mixed Second-Quarter Report, Soft Full-Year Outlook
LIF LIF -24.76%
Investor's Business Daily
|
| Aug-10 | |
| Jun-18 | |
| May-19 | |
| May-17 | |
| May-12 | |
| May-11 | |
| Mar-19 |
