Upstart Misses On EPS And Cuts Guidance As Macro Pressure Hits Balance-Sheet Income Despite Record Contribution Profit
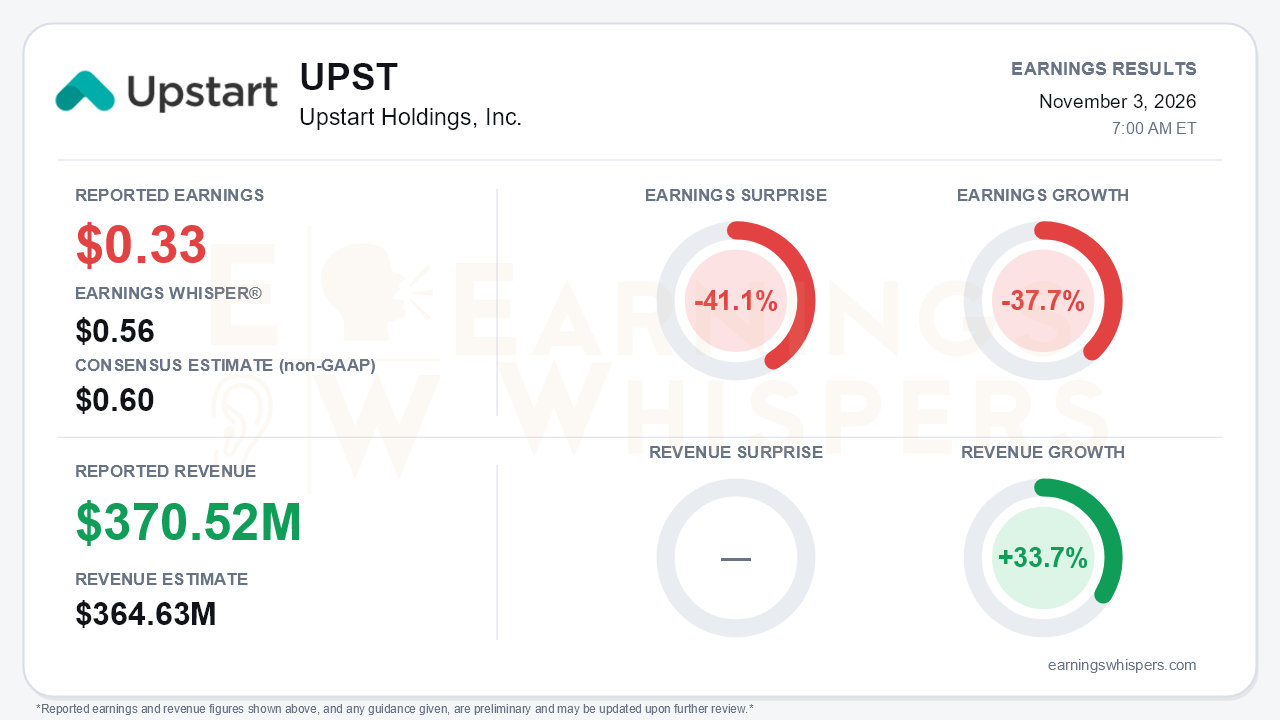
Upstart Holdings delivered a quarter in which its operating engine and its reported profit told two different stories. The AI lending marketplace reported third-quarter earnings of $0.33 per share. That fell well short of the $0.60 consensus and the $0.56 Earnings Whisper number, a 41.1% miss. Revenue of $370.52 million beat the $364.63 million consensus by 1.6% and grew 33.7% year over year. On Earnings Whispers' normalized basis, earnings fell 37.7%. That figure conflicts with the release, which shows GAAP diluted EPS rising to $0.33 from $0.23. The gap reflects the non-GAAP basis of the consensus and normalized comparison rather than the GAAP figure the company headlines. The more consequential news was the guidance. Management cut full-year total revenue to roughly $1.35 billion from $1.4 billion. It also lowered adjusted EBITDA to about $260 million (19% margin) from $294 million (21%), a target it had reiterated on both the Q1 and Q2 calls. That is the central tension: origination economics are improving while the macro backdrop erodes the income Upstart earns from loans it holds.
The quality of the quarter deserves careful separation. Revenue from fees was a record $364 million, up 41%. Contribution profit hit an all-time high of $218 million, up 48%, and contribution margin expanded to 60% from 55% in Q2 and 50% in Q1. The weakness sat below the fee line. Net interest income and fair value adjustments collapsed to roughly $6 million, down from about $17 million in Q2 and $31 million in Q1. Fair value and other adjustments were a $37.2 million drag, including $26.9 million of unrealized losses and charge-offs on loans. Adjusted EBITDA rose 26% to $89.3 million, but its margin slipped to 24% from 26%. Per-share results were also diluted by a weighted-average diluted count that climbed to 125.4 million from 109.7 million a year earlier.
The call kept a credible operating story intact. Secured products, auto and home, swung to a positive 17% contribution margin from negative 35% in Q2 and negative 96% in Q1. That arrived a quarter ahead of the Q4 break-even target. Unsecured contribution margin improved to 64% from 62%, and the take rate rose to 8.8% from 8.2%. Fixed expenses fell 3% sequentially, against guidance for low-single-digit growth. Capital efficiency also improved:
- Balance-sheet loans dropped to 4.8% of loans outstanding from 5.9%.
- Equity used fell to 9% of platform loans from 11.6% a year ago.
Management nudged fee revenue guidance up to $1.32 billion and set contribution profit at $750 million, above the original plan.
The forward risks are concrete. Upstart's macro index (UMI) averaged 1.50 in Q3, up from 1.41 in Q2, and has reached 1.53. That compares with the 1.4 to 1.5 range assumed in the original annual guide. Management cited inflation re-accelerating to 3.7%, rising consumer delinquencies and two-year Treasury yields up more than 115 basis points this year, about half of that in September. Volume momentum is fading as well:
- Q3 originations of $4.1 billion were slightly below Q2's $4.2 billion.
- Auto volumes declined.
- October daily originations ran 9% below September.
The Q4 outlook assumes UMI stays at or below 1.55 and implies a sizable fair value write-down. Management acknowledged it is hard to quantify fair value sensitivity if UMI moves higher. Discontinuing the conversion rate disclosure, which slipped to 18.6% from 19.4%, will not ease skeptics' concerns. The main offsetting catalyst is Upstart Bank, targeted for early 2027. Its roughly $404 million capitalization is expected to require no incremental equity, and management expects it to modestly lift take rates and net interest income.
The market had largely positioned for disappointment. Shares closed at $21.31 on November 2, down 38.4% from the $34.60 open after the August report. The stock sat 28.6% below its 200-day moving average and just 1.6% above a fresh 52-week low of $20.97 set that day. Investor sentiment slipped from mildly positive (0.07) to slightly negative (-0.02), a modest deterioration rather than capitulation. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Upstart's marketplace is getting more profitable and more capital-efficient faster than planned. Secured lending is ahead of schedule and fee guidance is rising. However, the company missed badly on earnings and broke a twice-reiterated EBITDA target as credit and rate pressure hit balance-sheet income. With October volumes softening and Q4 guidance hinging on UMI not worsening further, bears have legitimate ammunition. The bull case now rests on fee economics and the bank charter outrunning a deteriorating consumer.
Read our earnings preview for Upstart Holdings, Inc.: https://www.earningswhispers.com/article/UPST/21525
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| 5 hours | |
| 5 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-11 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 |
