Delek Faces A $7.59 EPS Bar Despite Warning Of Thinner Third-Quarter Refining Capture
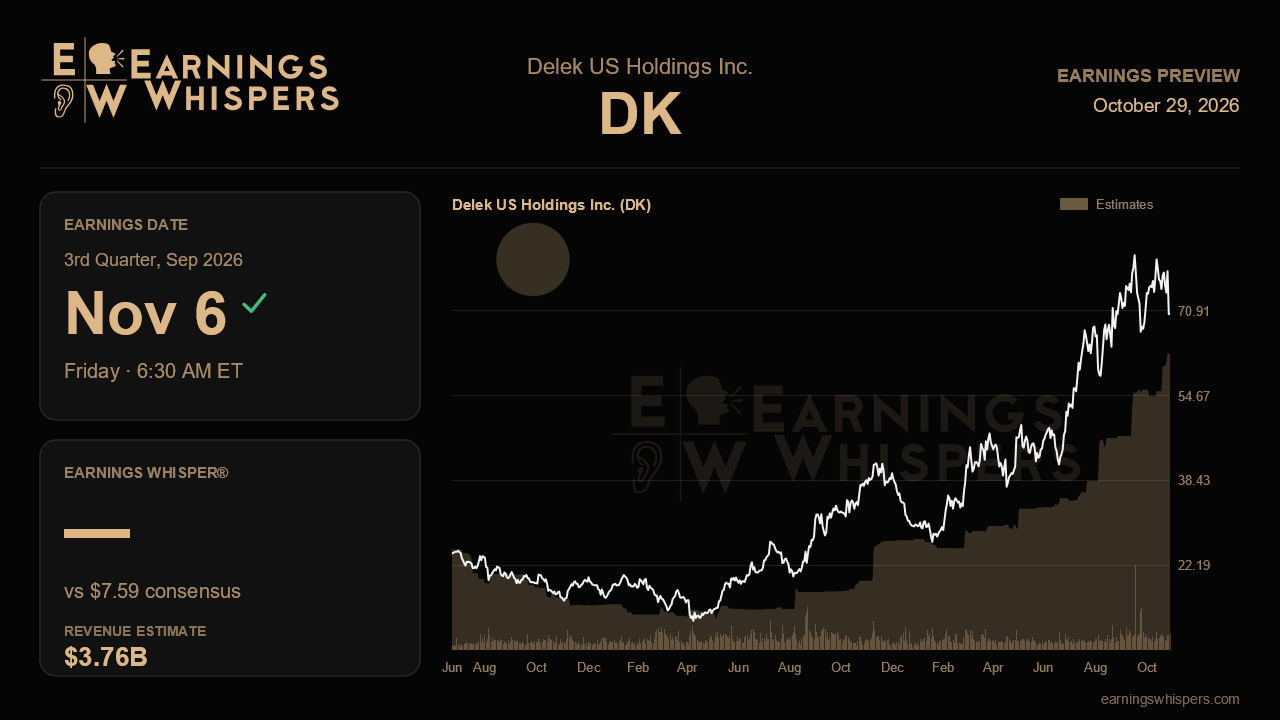
Delek US Holdings heads into its third-quarter report with an odd-looking setup. Last quarter, management told investors that the steep backwardation in the crude curve, which had padded second-quarter refining capture by roughly $6 to $7 a barrel, had flattened to about 50 cents. That is close to a dollar-for-dollar headwind to cracks. Yet Wall Street is asking for more, not less. Consensus calls for earnings of $7.59 a share on revenue of $3.76 billion, compared with $5.48 last quarter and just $1.52 a year ago. That would be a roughly fivefold year-over-year increase, with revenue up about 30% even as it slips from the prior quarter's $4.09 billion. The report has to explain how a refiner that flagged weaker capture can still post a sequential earnings jump of that size.
Part of the answer should come from volume and self-help, and those are the items to check first. Big Spring came out of its first-quarter turnaround running to plan, with better reliability, crude flexibility and yields, and management guided third-quarter throughput there to 68,000 to 73,000 barrels a day, up from 65,000 to 70,000. With no further planned turnarounds in 2026, the system should be capturing whatever margin the market offers. The Enterprise Optimization Plan is the other lever. Its run-rate target has climbed from an original $80 million to $120 million, to $180 million, then $200 million, and now $220 million or more, and management hinted that another step-change is coming. Having raised that target four times, Delek has set itself a high bar. A fifth increase, or real detail on the next chapter, would support the idea that margin gains are structural rather than borrowed from the commodity tape.
Midstream is the steadier piece of the story. Delek Logistics posted record adjusted EBITDA of about $144 million last quarter and reaffirmed 2026 guidance of $520 million to $560 million. Its sour gas solution, which includes Libby 2 processing, an acid gas injection well and sour gathering and compression, was nearing completion and is expected to drive a step change in gas volumes through the second half. Higher Delaware Basin gas throughput this quarter would confirm that. So would further progress toward the 80%-plus third-party EBITDA mix that underpins the eventual deconsolidation and sum-of-the-parts case. The new split disclosure of interest expense between Delek and its logistics arm suggests separation work is moving, and any update on the options management has floated, including M&A, an asset sale or unit buybacks, could matter as much as the quarterly numbers.
The wild card is small refinery exemptions. The grant of the Krotz Springs petition after a prior denial was the most important new item last quarter, and management read it as a favorable signal for pending 2025 petitions tied to more than $468 million of RVO obligations. Timing still depends on the EPA, and the tax treatment of monetized RINs has not been quantified. Because the basis behind the consensus figure is unclear, an exemption-related benefit could make the headline number hard to compare with estimates. The underlying refining margin and EBITDA excluding RVO will tell a cleaner story.
Expectations have clearly firmed. Sentiment has improved to 40.8% bullish from 28.8% ahead of the last report. The stock is up 7.4% since then while the S&P 500 slipped, and at $70.30 it trades well above its 200-day average of $52.46. It also sits about 15% below its post-earnings high of $82.27, so the market has already given back some of its early enthusiasm.
The central question is whether Delek's self-help, from Big Spring reliability and optimization savings to midstream growth, can offset the loss of the backwardation tailwind management itself warned about. If capture holds up better than feared and the EOP target moves higher again, the recovery narrative stays intact. If the earnings rely mainly on one-time regulatory credits, the market may question the quality of the quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Oct-08 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-18 | |
| Sep-04 | |
| Aug-31 | |
| Aug-28 | |
| Aug-17 | |
| Aug-14 |
