Delek US Posts A Record, Crack-Fueled Beat And Flips To Net Cash, But The Stock Had Already Faded From Its September Peak
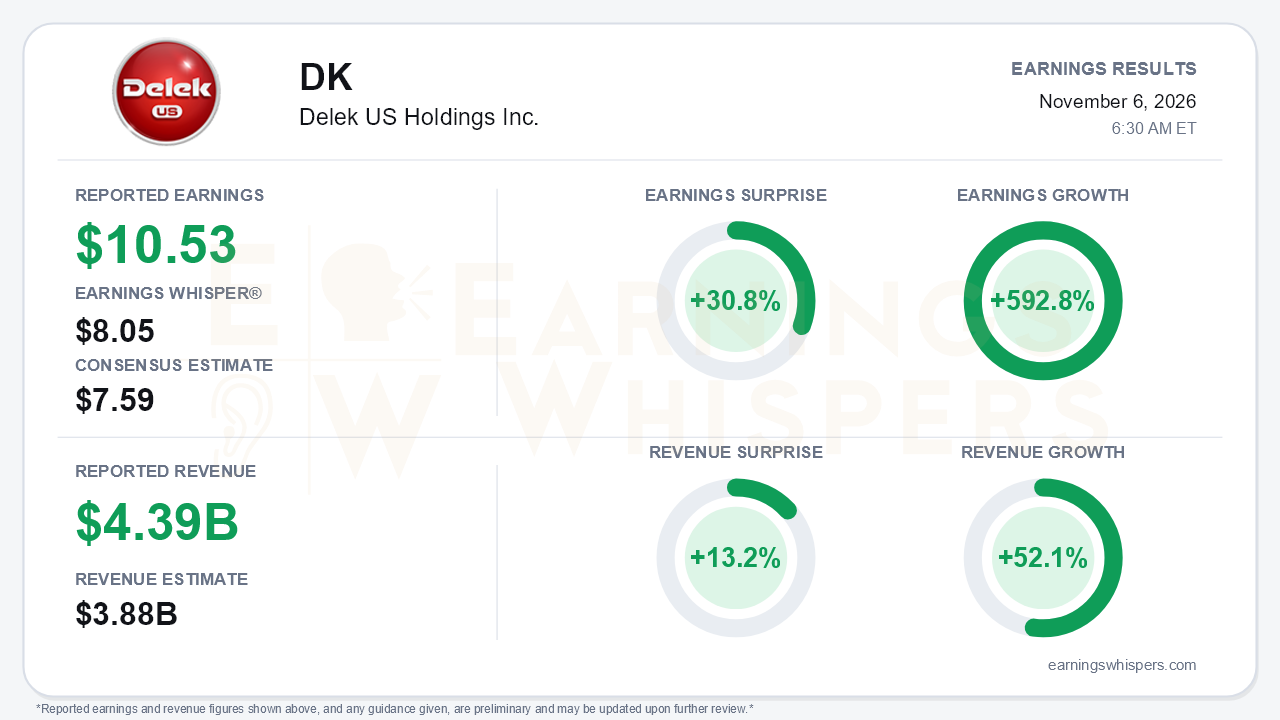
Delek US Holdings delivered the kind of quarter refiners rarely get. Adjusted earnings, excluding small refinery exemption (SRE) and RVO effects, came in at $10.53 per share, well above the $7.59 consensus and the $8.05 Earnings Whisper number, a 30.8% surprise. Earnings grew 592.8% from a year ago, when the comparable figure was just $1.52. Revenue of $4.392 billion beat the $3.88 billion consensus by 13.2% and rose 52.1% year over year. The central question is not whether the quarter was strong. It is how much of that strength is repeatable. Management used the windfall to change the balance sheet, while investors had already begun discounting the cycle before the report.
The headline numbers need some sorting. GAAP EPS of $18.22 was inflated by a $377.8 million RIN fair-value gain and the reversal of prior-period RVO shorts. The company's broader adjusted EPS of $13.55 still includes SRE benefits. The ex-SRE $10.53 is the cleaner operating figure, and it is excellent on its own terms. Benchmark crack spreads averaged 191.2% above prior-year levels, and the Gulf Coast 5-3-2 reached $63.52 versus $22.57. Delek captured that environment rather than just riding it:
- **Production margin:** ex-SRE refining production margin was $38.56 per barrel, up from $9.59.
- **Throughput:** crude utilization was 100.2% of nameplate.
- **Capture rates:** every plant improved, with Big Spring at 68.1% versus 50.7% and El Dorado at 52.9% versus 32.9%.
- **Costs:** operating expense held at $5.36 per barrel.
The sequential trajectory is even more striking. On the call, ex-SRE adjusted EBITDA was cited at about $129 million in the first quarter, about $490 million in the second, and about $1.04 billion in the third.
The call converted operating momentum into capital-return and balance-sheet commitments:
- **SREs:** all four 2025 exemptions were granted, with about $425 million in cash expected in the fourth quarter and a total accounting benefit of $750 million to $800 million at current RIN prices.
- **Leverage:** Delek standalone moved from $273.8 million of net debt at year-end to $21.9 million of net cash. The $850 million term loan is slated for repayment this quarter, and standalone quarterly interest guidance fell to $12-17 million from $28-33 million, heading toward roughly $10 million.
- **Shareholder returns:** the dividend rose about 18% to $0.30. Buybacks stepped up from $20 million in the second quarter to $50 million in the third, with up to $100 million planned for the fourth.
- **Targets:** the Enterprise Optimization Plan target rose again to at least $250 million. The mid-cycle free cash flow framing moved up to $700-800 million. Delek Logistics' 2026 EBITDA guidance edged up to $530-560 million.
The CEO called it a landmark quarter and described Delek as the cheapest refiner. The tone has clearly escalated.
Bears still have legitimate ammunition. Analysts pressed on RIN transparency, and management would say only that the company is "in compliance." It declined to confirm being current, which leaves open the possibility of an uncovered short that depends on future exemptions. Operating cash flow of $567.4 million was held back by an $808.8 million working-capital outflow. Management tied most of that to SRE receivables and timing items, but it still blurs the cash picture for now. Other soft spots:
- **Market dependence:** earnings rest heavily on cracks lifted by Middle East and Eastern Europe disruptions and elevated freight rates, conditions that can normalize quickly.
- **Throughput guide:** El Dorado's fourth-quarter range of 67-72 kbpd is below the third quarter's 78-83 kbpd.
- **Other segments:** asphalt lost $4.6 million, and logistics EBITDA was essentially flat sequentially at about $143 million.
- **Open questions:** the 2027 turnaround schedule and buyback cadence were left undisclosed.
The market setup is more complicated than the surprise implies. As of the pre-report snapshot, shares traded at $62.49. That is 4.6% below the open after the August report and 24% below the $82.27 52-week high set on September 18, during the inter-earnings period. The stock sat closer to the bottom of its quarterly range, 10.9% above the August low of $56.34, though still a healthy 16.5% above its 200-day moving average of $53.66. Investor sentiment stayed positive but cooled, slipping from 0.29 to 0.21. The pattern is consistent with investors who believed the margin story but grew wary of paying peak multiples on peak cracks.
The bottom line is that Delek beat on every headline measure. More importantly, it used an extraordinary margin environment and an SRE windfall to build a structurally stronger company, with standalone net cash, lower interest costs, a larger dividend and explicit buybacks. The debate now shifts from earnings power to durability: how long elevated cracks persist, how clean the RIN position really is, and whether the working-capital drag reverses as promised in the fourth quarter.
Read our earnings preview for Delek US Holdings Inc.: https://www.earningswhispers.com/article/DK/22479
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Oct-08 | |
| Sep-24 | |
| Sep-24 | |
| Sep-24 | |
| Sep-18 | |
| Sep-04 | |
| Aug-31 |
