Bull of the Day: Delek US Holdings (DK)
The oil and gas sector has shown relative outperformance throughout the year, and amid the recent rise in volatility and correction in AI stocks, it continues to stand out.
While other defensive sectors, including healthcare and consumer staples, have also attracted investor interest, energy has additional catalysts, particularly renewed geopolitical tensions surrounding the conflict in the Middle East.
Delek US Holdings (DK), an independent refiner, transporter and marketer of petroleum products, boasts a top Zacks Rank and strong price action.
More specifically, Delek is a bet on refining margins, commonly measured by crack spreads, or the difference between the price of crude oil and the petroleum products refined from it. These spreads have benefited from disruptions and uncertainty surrounding the conflict in the Middle East, and a continuation of those tensions could keep margins elevated.
That makes Delek a more targeted way to express a bullish view on the energy sector and the persistence of geopolitical tensions, though an easing of the conflict and normalization of refining margins would present risks to the thesis.
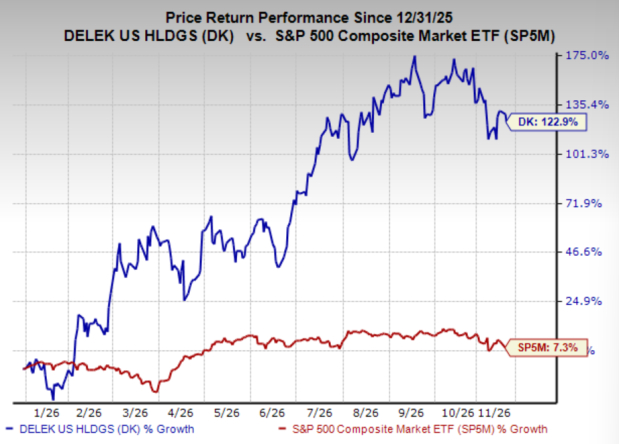
Image Source: Zacks Investment Research
DK Shares Gain Following Upgrades but Falls on Earnings
Analysts have revised DK’s earnings estimates sharply higher as crack spreads widened to record levels this fall, lifting the stock to a Zacks Rank #1 (Strong Buy).
Its most recent earnings report was a blowout, with record net income of $1.13 billion and refining EBITDA of $1.24 billion, up from $697 million a year ago. Management credited the quarter in part to its “industry leading distillate and jet yield.” Diesel and jet fuel made up about 40% of DK’s refinery output in Q3, which puts the company squarely in the part of the fuel market where supply is tightest.
But shares wobbled after the results. The stock has since regained its footing, though the initial reaction suggests the market may be betting that crack spreads will soon revert toward their historical averages.
For investors looking to hedge against the possibility that this doesn’t happen, and that spreads stay elevated because of a prolonged Middle East conflict or continued tightness in refined product markets, DK offers a compelling opportunity.
Below, we’ll look at the game theory behind why crack spreads could stay elevated longer than the market expects.
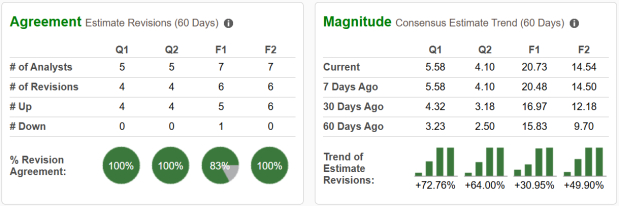
Image Source: Zacks Investment Research
Why Refining Margins May Stay Elevated
Start with Iran. The IRGC has little reason to settle quickly. Each month Hormuz stays disrupted, Tehran adds pressure on the US economy and builds leverage at the negotiating table. It has refused to send its enriched uranium abroad, which Washington wants included in any first deal, and its record over the past year gives it little reason to trust US guarantees.
Even if a deal comes, the refined product market doesn’t snap back. The headline 3-2-1 crack spread has fallen by about half from its September record, but nearly all of that drop came from gasoline, which typically weakens after the summer driving season. Diesel margins have barely moved and are still roughly three times their historical norm.
The supply picture behind diesel keeps tightening. US distillate inventories are 8% below their five-year average and below even the 2022 lows for this time of year. Russia is restricting diesel exports through January, and Middle East crude flows have recovered much faster than fuel supply. Cheaper crude and scarce products are exactly the mix that widens refining margins.
This is where DK’s product mix matters. Diesel and jet fuel made up roughly 40% of DK’s refinery output last quarter. At current benchmark spreads, a barrel of diesel earns about four times the margin of a barrel of gasoline, so DK’s distillate output likely generates around three-quarters of its refining margin.
The market is pricing DK’s Q3 as the peak. For diesel-driven margins, it could be closer to a new floor.
Should Investors Buy Shares in DK?
Delek offers investors an interesting way to position for continued tightness in energy markets, particularly in diesel and other refined products.
The stock's top Zacks Rank reflects sharply rising earnings expectations, while its recent price action suggests investors remain skeptical that current refining margins are sustainable.
That skepticism is understandable as refining is a cyclical business, and a resolution to the conflict in the Middle East could bring substantial pressure on crack spreads and DK shares.
However, with distillate inventories already tight and supply disruptions unlikely to resolve overnight, there is a credible case that elevated margins could persist longer than expected.
For investors who share that view, DK offers a compelling opportunity, with the potential for further earnings upside if refining margins remain elevated into 2027.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Delek US Holdings, Inc. (DK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Mentioned In This Article
Latest News
| 4 hours | |
| 13 hours | |
| Nov-11 | |
| Nov-10 | |
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Oct-08 | |
| Sep-24 | |
| Sep-24 |
