EVgo's Q3 Report Tests Whether A Strong Charging Business Can Offset A Guidance Cut
EVgo heads into its third-quarter report with two stories that do not fit neatly together. Its core fast-charging network keeps growing at a double-digit clip with widening margins. Yet management cut full-year revenue and adjusted EBITDA guidance last quarter, citing a slow-ramping 2025 stall cohort and a shrinking forecast for the number of EVs on the road. Then it announced a Tesla supercharger deal that it says roughly doubles its addressable market starting in 2027. This report is the first real chance to see which narrative is setting the pace.
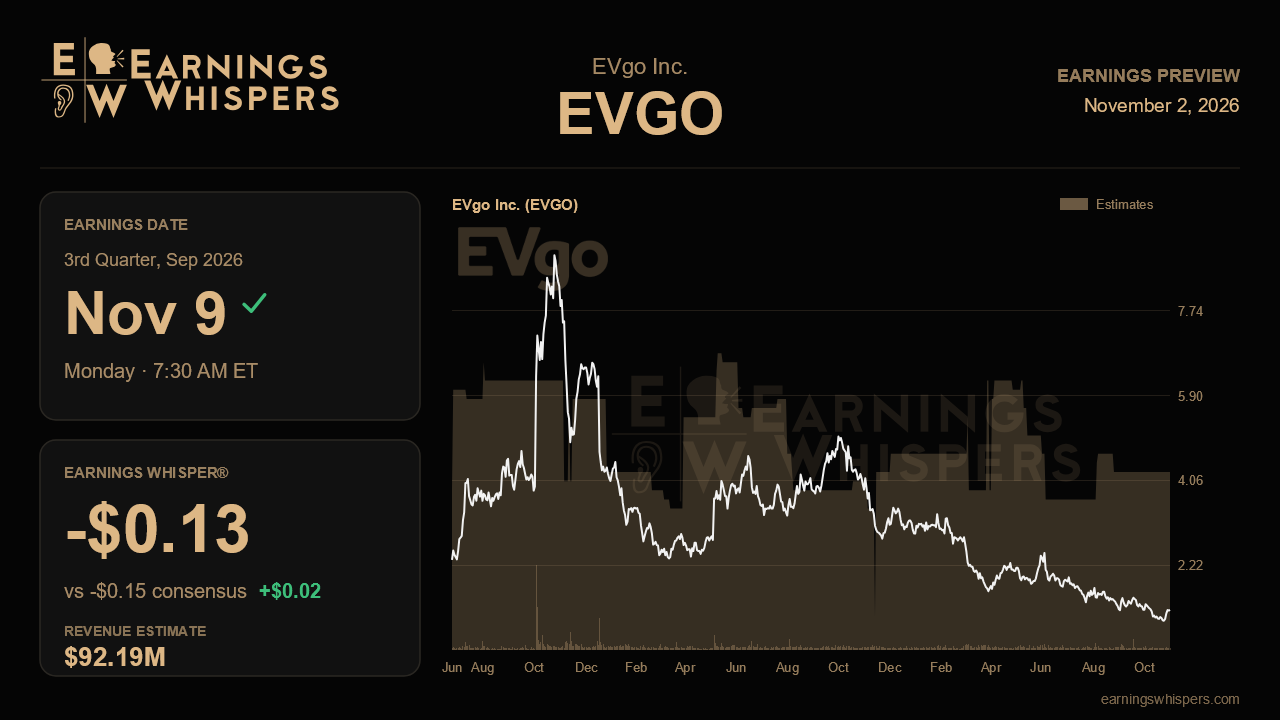
The Street expects a loss of $0.15 per share on revenue of about $92.2 million. That revenue is essentially flat with the year-ago $92.3 million, while the loss would be noticeably wider than last year's $0.09. A sequential jump from the second quarter's $82.6 million is built into the numbers, so the bar is not trivial. The whisper number sits at a loss of $0.13, a modestly better result than consensus. That points to a market quietly hoping for some relief on costs, consistent with management's trimmed G&A outlook. The more telling gap is on the full year. Consensus revenue of roughly $440 million sits above the top of EVgo's lowered $400 million to $430 million range. That suggests some estimates have not fully caught up with the cut. Any reaffirmation near the midpoint could pull the Street lower, and another trim would sting.
The swing factor is the mix between charging and everything else. Last quarter, charging network revenue rose 19% to $61 million, while reported revenue fell 16%. The drag came from weaker Xtend and autonomous-vehicle work. Management lifted its Xtend outlook to $90 million to $95 million, so this quarter should show that piece recovering. AV and ancillary revenue remains lumpy, with no new deployments last quarter. Strong charging growth paired with a rebound in Xtend would validate the view that the guidance cut was about timing and cohort math rather than demand erosion. Another quarter of shrinking non-charging revenue would make the full-year range look stretched.
Utilization deserves close attention. Daily throughput per stall slipped 2% last quarter. Several pressures weighed on it: softness in legacy 50 and 100 kW equipment, fading OEM charging credits, and the slower 2025 vintage, which is not maturing on the roughly 12-month schedule earlier cohorts followed. Stabilizing per-stall throughput, or evidence that the 2025 cohort is catching up, would ease concerns behind the lowered long-term assumption of 425 to 475 kWh per day. Continued declines would suggest the problem runs deeper than old hardware. Charging gross margin is also worth tracking, after it reached 39% on a trailing basis.
The build schedule matters too. EVgo expects about 60% of its 2026 stall additions in the fourth quarter, which leaves little room for slippage against a 1,350 to 1,625 stall target. Any update on early Tesla V4 deployments, growth in NACS throughput, or lease signings tied to the projected 2027 ramp would help show that the new catalyst is moving from announcement to execution.
The market has not been patient. Shares have fallen about 17% since the last report, against a 2.6% slip in the S&P 500. At $1.26, the stock trades well below its 200-day average of $1.93 and in the lower half of its post-earnings range of $0.98 to $1.69. That range sits entirely beneath the prior quarter's band, and sentiment has grown more bearish. The low bar offers some cushion. Still, the central question is whether EVgo can hold its reduced 2026 outlook while showing per-stall demand bottoming. If it can, the Tesla story gets room to breathe. If not, the guidance cut may look like the first step rather than the last.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 min | |
| 3 hours | |
| Oct-30 | |
| Sep-30 | |
| Sep-29 | |
| Sep-29 | |
| Sep-09 | |
| Sep-09 | |
| Aug-11 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-22 | |
| Jun-15 |
