EVgo's Core Charging Business Strengthens, But A Third Guidance Cut And LS Power's $2 Bid Overshadow The Quarter
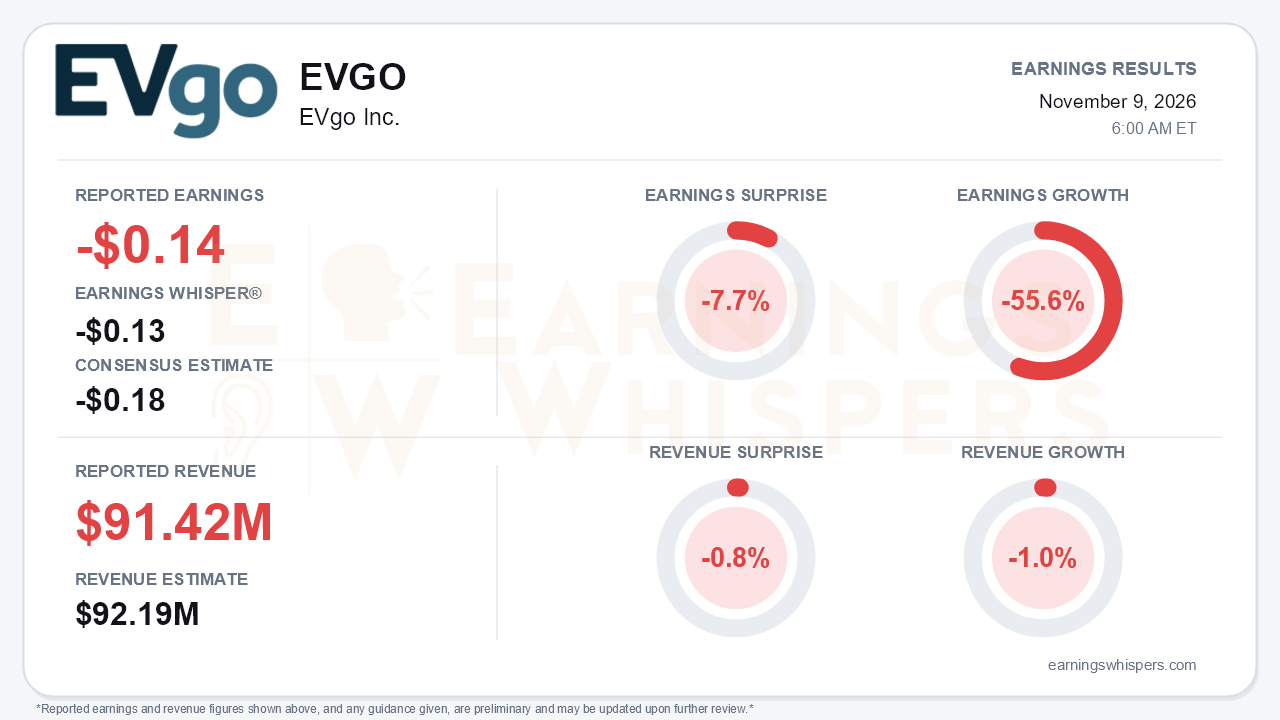
EVgo reported a third-quarter loss of $0.14 per share on revenue of $91.42 million. The loss was narrower than the -$0.18 consensus but wider than the -$0.13 Earnings Whisper number, so the quarter counts as a 7.7% miss against the expectation that mattered most. Revenue fell 1.0% year over year and missed consensus by 0.8%. Earnings fell 55.6% from a year ago, when the loss was $0.09 per share. The more consequential news came alongside the numbers. Management cut full-year guidance for a third consecutive quarter, slashed its stall-deployment plans, and disclosed that majority holder LS Power had made an unsolicited, non-binding proposal to take the company private at $2.00 per share. That is the central tension: the core charging business had arguably its best quarter yet, while the growth story built around it shrank again.
The operating metrics themselves were genuinely encouraging.
- **Charging revenue:** Charging network revenue rose 29% to $71.8 million, an acceleration from roughly 19% growth in Q2 and 18% in Q1.
- **Charging margin:** Charging network gross margin reached 39.0%, up from about 36% in the prior two quarters and 35.2% a year ago.
- **Adjusted margins and EBITDA:** Adjusted gross margin jumped to 35.4% from 28.9%. The adjusted EBITDA loss narrowed to $3.5 million, from $10.6 million in Q2 and $5.0 million a year earlier.
The headline revenue decline came almost entirely from non-charging lines. eXtend revenue fell 49% to $16.2 million, and AV and ancillary revenue dropped 25%. Below the gross line, the picture was much weaker. GAAP net loss widened to $49.2 million from $28.4 million, driven by $17.0 million in disposal and impairment losses, a 39% jump in GAAP G&A, and interest expense that more than doubled as long-term debt climbed to $312 million.
The call explained why the improving margins did not reassure. Throughput per stall fell 4% year over year to 283 kWh, and the usual summer seasonal lift never arrived. Excluding OEM charging-credit programs, throughput per stall rose 7%, but management acknowledged two soft spots:
- late-2025 site cohorts are ramping slowly;
- OEM credit customers are converting to paying retail customers more slowly than expected.
The guidance reset was broad:
- **Revenue:** $375–$400 million, down from $400–$430 million last quarter and as high as $470 million originally.
- **Adjusted EBITDA:** -$30 million to -$15 million. The original range reached +$20 million.
- **Profitability framing:** The Q4 positive-EBITDA expectation and the annualized second-half EBITDA framing were both dropped.
- **New stalls:** 1,075–1,275, down from 1,350–1,625.
- **Public and AV stalls:** cut to 600–750 from 950–1,175, with gross capex about $100 million lower.
- **AV/ancillary revenue:** trimmed to $30–$45 million.
- **NACS stalls:** the year-end target was lowered to about 400 from 500.
Talk of 2027 builds reaching 2.5–3x 2025 levels gave way to "smaller" cohorts. Management's tone shifted from last quarter's argument that the stock was mispriced to a defensive emphasis on cost control. The 2026 adjusted G&A outlook was lowered to roughly $145 million, and 2027 adjusted G&A is targeted at least 15% below the prior implied level.
There are still real catalysts. The first EVgo-branded Tesla Supercharger site opened in Chicago, with Houston expected in the fourth quarter. NACS connectors reached 290, and management says they deliver 35% faster charge rates than CCS. Expanded Brixmor and Regency Centers partnerships add more than 900 chargers to the pipeline, eXtend stall guidance was raised, and a 750 kW architecture is slated for 2027.
The balance sheet, however, gives bears legitimate ammunition:
- Cash fell to $98.7 million from $151 million at year-end.
- Year-to-date operating cash burn tripled to $57.1 million.
- Capex net of offsets surged 482% in the quarter as tax-credit and capital-build proceeds shrank.
More broadly, lower EV adoption forecasts and the loss of federal incentives cloud the longer runway.
The LS Power proposal now dominates the market setup. Shares hit a 52-week low of $0.98 on October 23 and then nearly doubled to a quarter high of $1.95 on November 2, the day the board received the bid. As of the pre-report snapshot, the stock sat at $1.83. That is 20.4% above the open following the August report, about 3.6% below the $1.90 200-day moving average, and below the $2.00 offer. A special committee is evaluating the proposal, no decision has been made, and nothing guarantees a deal. Investor sentiment remained negative and slipped modestly, from -0.21 to -0.25, which suggests the rally was driven by the bid rather than renewed confidence in the standalone plan.
The proposal also reframes the fundamentals. A controlling holder bidding $2 after three guidance cuts effectively puts a ceiling-like reference point on the debate. For minority holders, the question shifts from whether EVgo can reach sustained profitability to whether the special committee can extract a better price.
The bottom line is that EVgo's best-ever charging margins and accelerating core revenue were overwhelmed by a whisper miss, a third straight guidance cut, a shrinking build plan, and rising cash burn. With the stock now trading largely as a function of LS Power's $2 proposal, the near-term story rests more on the special committee's process than on the improving unit economics the quarter delivered.
Read our earnings preview for EVgo Inc.: https://www.earningswhispers.com/article/EVGO/22562
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Sep-30 | |
| Sep-29 | |
| Sep-29 | |
| Sep-09 | |
| Sep-09 | |
| Aug-11 |
