MasterBrand's First Full Merged Quarter Tests Whether Synergies Can Outrun Eroding Cabinet Margins
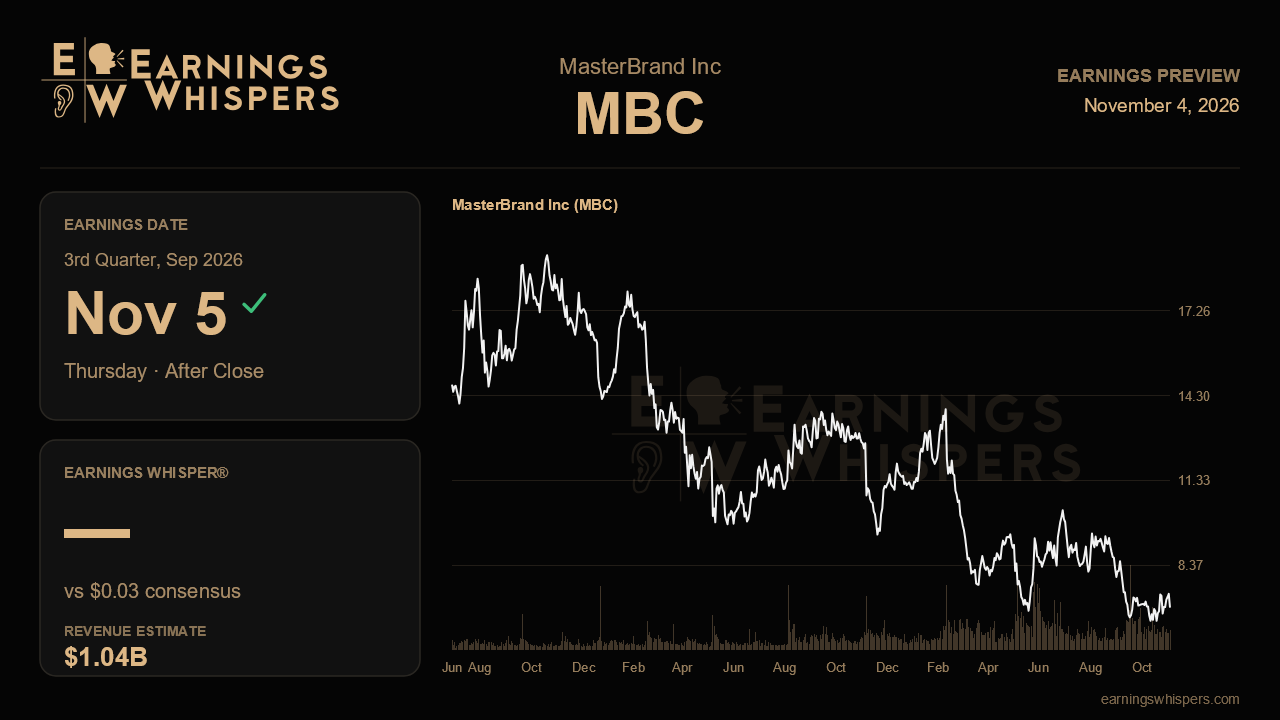
MasterBrand enters its third-quarter report with a story split down the middle. The American Woodmark merger has closed, the cost synergy target has been lifted, and management sounded more confident last quarter than it has in some time. Yet the core cabinet business keeps losing margin, leverage is well above where the company once promised it would be, and the stock has been marked down hard since the last report. The September quarter is the first full three months of the combined company, which makes it the first clean test of whether self-help can carry the weight while the housing-related market stays soft.
Wall Street has set a very low bar on earnings. Consensus calls for $0.03 a share, down about 91% from $0.33 a year ago and below the $0.05 posted last quarter. Revenue comparisons will look large because a full quarter of American Woodmark now sits in the numbers. That gain comes from the acquisition, not from organic growth, and a year-ago base of $698.9 million says little about underlying demand. The more useful yardstick is management's first combined outlook for the second half of 2026: $2.05 billion to $2.11 billion in sales and $129 million to $149 million in adjusted EBITDA. Spread evenly across two quarters, that implies roughly $1 billion of quarterly sales at an adjusted EBITDA margin in the high single digits at best. Results tracking toward the lower half of that range would undercut the credibility management tried to build by issuing the outlook in the first place.
Margins are the main event. Legacy adjusted EBITDA margin fell to 8.4% last quarter from 13.0% about a year earlier, and legacy gross margin dropped 540 basis points year over year to 27.4%. Management expects no market recovery until 2027 and is still planning for the addressable market to shrink by a mid-single-digit percentage. That leaves synergies, plant consolidation and pricing as the levers that have to show up. Roughly $30 million of annualized savings had been executed by the end of July, with about $15 million expected to land in the second half. This quarter should show whether those savings are reaching the income statement or being absorbed by fuel and freight inflation, new Section 338 and 301 tariff layers, and American Woodmark's excess fixed capacity. That business was running at only a 7% to 8% EBITDA margin, so any sign the two announced plant closures are improving absorption would count as real progress.
Cash and leverage form the second test. Free cash flow of $128.6 million last quarter, nearly double the prior year, was a bright spot, helped in part by tariff refunds of which $10.4 million of an expected $14.9 million had already arrived. Net leverage stood at 3.9 times reported and 3.4 times on a covenant basis, and the sub-2 times goal has been pushed out to the end of 2028, delaying any return of buybacks. Steady debt reduction would support the deleveraging timeline. A stall would raise questions, especially with the Section 232 tariff set to climb to 50% on January 1, 2027, a risk management has said could stretch the timeline further.
The market has already taken a skeptical view. Shares have fallen 22.3% since the last report, about 19.5 percentage points worse than the S&P 500. At $6.89 the stock sits well below its 200-day moving average of $8.82 and near the bottom of its post-earnings range of $6.17 to $9.54. Sentiment readings lean bearish as well. Low expectations can cushion a modest result, but they also signal that investors want evidence rather than promises ahead of the Investor Day planned for early 2027.
The central question is whether the synergy machine is visibly working. If combined margins hold near the implied second-half outlook, synergy capture tracks the stated pace and the outlook is reaffirmed, the case for structurally higher profitability stays intact. If margins slip again and the outlook is trimmed, the raised synergy target will look like a partial offset to a deteriorating base rather than a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-26 | |
| Oct-26 | |
| Oct-06 | |
| Sep-15 | |
| Sep-03 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-07 | |
| May-28 | |
| May-27 |
