MasterBrand's Refund-Aided Beat Is Overshadowed By A Guidance Cut, Rising Leverage And A Delayed Recovery
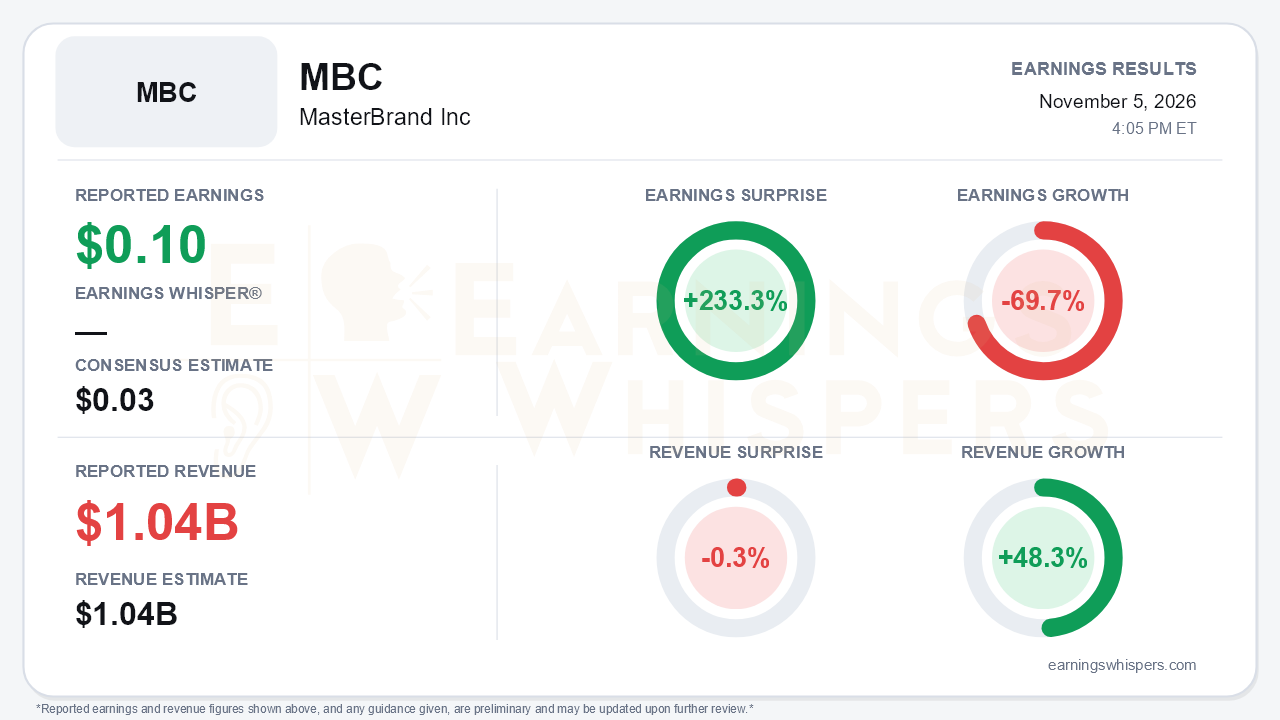
MasterBrand cleared a very low bar in its first full quarter as a combined company with American Woodmark, but the rest of the report reset expectations lower. Adjusted earnings of $0.10 per share beat the $0.03 consensus by 233.3%. Even so, adjusted EPS fell 69.7% from a year ago. Revenue of $1.037 billion rose 48.3% on the acquisition and missed consensus by 0.3%. On a GAAP basis, the company swung to a net loss of $9.2 million, or $(0.05) per share, from a $0.14 profit a year earlier. The central tension is simple: the quarter beat estimates, but management cut its market view, guided the fourth quarter below estimates to an adjusted loss, and pushed out both its demand-recovery and deleveraging timelines.
The quality of the beat deserves scrutiny. Adjusted EBITDA of $86.0 million included $10.9 million of IEEPA duty refunds. Without that benefit, adjusted EBITDA would have been roughly $75 million, and the margin would have been closer to 7% than the reported 8.3%. Margin pressure was broad:
- Gross margin fell 660 basis points to 24.6%.
- Lower volume and weaker fixed-cost leverage weighed on results.
- Inflation outpaced pricing.
- Product mix and customer trade-downs hurt.
- American Woodmark's structurally lower margins were folded in.
Per-share comparisons are also heavily diluted. Diluted shares jumped to 203.5 million from 129.5 million, while interest expense rose to $24.4 million.
Beneath the headline, there is a genuinely constructive thread. Legacy MasterBrand sales of $681.1 million fell only 2.5% in a market management described as down mid- to high-single digits. That is a clear improvement from declines of 5.6% in the second quarter and 6.4% in the first, and it points to real share gains in both new construction and repair-and-remodel. Integration is also running ahead of plan:
- About $11 million of synergies have been realized to date, roughly $9 million of them in the third quarter.
- Actions now underway are expected to deliver more than $50 million of run-rate synergies, up from about $30 million executed as of the second quarter.
- Second-half synergies are now expected to exceed the prior target of about $15 million.
- The target of more than $100 million by year three was reaffirmed.
Management is pursuing footprint actions at five plants, including Kinston, a Gap City line and three Mexico facilities. Third-quarter free cash flow of $61 million compared with $40 million a year earlier. The call preserved a credible self-help story.
The macro and balance-sheet picture, however, moved decisively the wrong way:
- **Market outlook:** Management now expects the 2026 addressable market to fall high-single digits, after holding at mid-single digits since late 2025.
- **Demand:** Management said demand decelerated in September, after mortgage rates moved above 7%, and that the weakness has continued into the fourth quarter.
- **Q4 guidance:** Fourth-quarter guidance calls for sales of $958–$988 million, adjusted EBITDA of $38–$48 million (a 4.0%–4.9% margin) and an adjusted loss of $(0.12) to $(0.08) per share. That implies second-half results below the sales range given last quarter and EBITDA at the low end of its range.
- **Free cash flow:** The full-year forecast was cut to roughly breakeven from "in excess of net income." With $43.6 million generated through 39 weeks, that implies a cash outflow in the fourth quarter.
- **Leverage:** Net leverage rose to 4.3x from 3.9x last quarter, and the target of below 2x slipped a full year to the end of 2029.
The risk list is also longer:
- CFO Andi Simons departed, and an interim CFO is in place.
- The company is now planning for the Section 232 cabinet and vanity tariff to rise to 50% on January 1, 2027.
- Fuel and freight inflation is outpacing pricing.
- American Woodmark sales fell about 9% on a pro forma basis.
- Management warned that a recovery previously framed for 2027 may be pushed out further.
The tone shifted from last quarter's "transformational" optimism to a defensive focus on what the company can control.
The market had already been leaning against the stock. Shares entered the report at $7.51, down 15.3% from the open following the August release. They also sat 14.6% below the 200-day moving average of $8.79 and 21.3% below the inter-earnings high of $9.54 set on August 13. The stock hit a 52-week low of $6.17 on October 14, then rebounded about 22% into the print, so some relief was already priced in ahead of a report that delivered a beat paired with a guidance cut. Investor sentiment stood at -0.31, a moderately negative reading consistent with skepticism toward a newly levered, tariff-exposed housing name.
The bottom line is that MasterBrand's quarter splits cleanly into two stories. The controllable side is improving: share gains in the legacy business, synergies ahead of schedule and cost actions that should benefit 2027. The uncontrollable side is deteriorating faster: a weaker housing market, a Q4 guide to an adjusted loss, breakeven cash flow, 4.3x leverage with a delayed deleveraging target, a looming 50% tariff and a CFO vacancy. The beat was real but refund-assisted. For investors, the investment case now rests on synergy execution outrunning a recovery that management itself says may come later than planned, and bears have legitimate ammunition until the market stabilizes.
Read our earnings preview for MasterBrand Inc: https://www.earningswhispers.com/article/MBC/22840
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-26 | |
| Oct-26 | |
| Oct-06 | |
| Sep-15 | |
| Sep-03 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-07 | |
| May-28 | |
| May-27 |
