Dow, Nasdaq Futures up Triple Digits as Oil Rally Cools
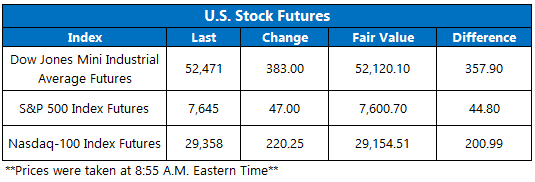
Following a fourth-straight loss for all three major indexes, stock futures are pointing higher this morning as oil prices begin to cool off. Futures on the Dow Jones Industrial Average (DJI) and Nasdaq-100 Index (NDX) are up triple digits, while the S&P 500 Index (SPX) sits firmly higher as well.
Investors are also unpacking August's consumer price index (CPI), which rose 0.4% month over month and 3.4% year over year, both in line with expectations. Core CPI, however, rose 0.3% for the month, slightly hotter than anticipated. Treasury yields are holding steady following the report.
Continue reading for more on today's market, including:
- Rideshare stock due for a short-term bounce.
- Call traders continue to target Apple stock after product launch.
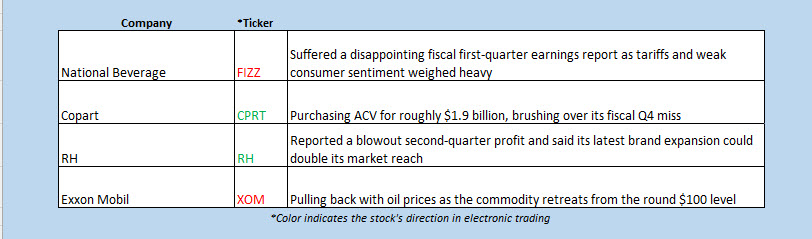
- Plus, three stocks moving after earnings.
5 Things You Need to Know Today
- The Cboe Option Exchange saw roughly 2.3 million call contracts and 1.4 million put contracts traded on Thursday. The single-session equity put/call ratio fell to 0.60, while the 21-day moving average remained at 0.59.
- Kroger Co (NYSE:KR) is down 2.2% premarket, after the company posted mixed second-quarter results and slashed it annual sales growth guidance. The grocery giant reported slightly better-than-expected earnings of $1.09, while revenue of $34.62 billion missed estimates. Coming into today, KR is down 8.8% year to date.
- Oracle Corp (NYSE:ORCL) is up 5.8% before the bell, looking to cut into some of its 21.5% year-to-date deficit, after the company's fiscal first-quarter earnings and revenue surpassed analyst expectations. Plus, revenue from cloud infrastructure more than doubled to $7.4 billion.
- Adobe Inc (NASDAQ:ADBE) is down 3% in electronic trading, despite better-than-expected fiscal third-quarter results, including record revenue of $6.76 billion, as its current-quarter forecast disappoints investors. Eyeing its fifth-straight session in the red, ADBE is down 28.9% in 2026.
- The Federal Reserve's interest rate decision is the big ticket item next week.
European Markets Head for Worst Week Since April
Asian stock market sentiment stayed sour to end the week. Concerns arose that the Bank of Japan (BoJ) would hike interest rates at its next meeting, after wholesale inflation data showed the yen-based import price index rising 24.8% in August and 7.6% year-over-year, the latter surpassing the 7.4% estimate. In response, the Nikkei shed 1.9%. Rounding out the region, South Korea’s Kospi lost 1.8%, China’s Shanghai Composite fell 1.2%, and Hong Kong’s Hang Seng index backpedaled 0.6%.
European markets are faring better, moving higher on the back of rising travel and leisure stocks and fresh economic data. In the U.K., investors are digesting gross domestic product (GDP) data that showed a 1.6% year-on-year rise for July, surpassing the 1.2% expectations. For the month, GDP added 0.4%, well above the flat estimate. London’s FTSE 100 and France’s CAC 40 were both last seen up 0.7%, while Germany’s DAX sports a 0.6% gain. Despite today’s pop, the indexes are pacing for their worst weeks since April.
Mentioned In This Article
Latest News
| 7 hours | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-04 | |
| Sep-03 | |
| Sep-02 | |
| Sep-01 | |
| Sep-01 | |
| Sep-01 | |
| Aug-31 | |
| Aug-28 | |
| Aug-27 |
